Over 10 Lakh Life Insurance Agents Exited The Industry Over The Past 4 Years

Due to introduction of stricter syllabus and a tough business environment, over 10 lakh life insurance agents have exited the industry over the past four years.

Life insurance companies has terminated over 36 lakh agents and hired around 26 lakh agents over the past four years. This marks a net decline of 10 lakh agents for the industry.

Agency is the main channel for distribution in the life insurance industry. The fall in the total number of agents is a big challenge to the industry.

The life insurance industry has seen a decline in new business premium collection for the past three years, particularly in the Unit-Linked Insurance Plan (ULIP) segment.

After rampant mis-selling in 2010, the Insurance Regulatory and Development Authority (IRDA) revamped ULIP norms by increasing the lock-in period and cutting commissions on their sale for agents from average of 15% of the premium collected to 5-6%. This led to a massive dip in ULIP sales and a shift in focus to traditional insurance products.

In 2011, the IRDA introduced a new, tougher syllabus and examination pattern for those seeking to get an agency license. This resulted in big drop in the number of agents clearing the exam.

The IRDA identified the cut-off percentage of 50% as one of the major reasons for the fall in the number of agents. Subsequently, 35% was made the minimum pass mark.

Earlier only 40% of the agents appearing were able to clear the exam but after the reduction in the minimum pass percentage, over 80% have been able to pass.

vinay mohanty

Eyes, nose or ears — drop the habit

Using over-the-counter drops for minor irritations without asking a doctor could have disastrous consequences.

At the age of 27, Aabha has developed cataract in both her eyes.This isn’t the result of a mysterious medical condition. It is the consequence of using a steroid-based eye drop every night before going to bed for the past year.

 “My mother used these drops, so I bought them from the chemist too. The attendant said the medicine had no side-effects. I just used them to clean my eyes so I could prevent vision loss,” said Aabha (name changed), who will now have to undergo a surgery for the condition, in which the inside of the lens gets cloudy, affecting the patient’s vision. “I can’t blame the chemist. A drug that cost just Rs. 10 has damaged my eyes. I regret self-medicating,” she said.

Medicinal drops that promise quick relief from eye or ear infections and nasal decongestion can harm you if used for too long, say doctors. Patients cause major damage to their sense organs by using medicines to treat minor irritation without visiting a physician.

“To get relief from eye irritation, the best thing to do is to relax the eyes and reduce computer and television usage. I advise patients to clean their eyes with warm water, which helps kill microorganisms,” said Dr Darshan Chudgar, an ophthalmologist at Kohinoor hospital, Kurla.

Apart from purchasing drops by consulting attendants at chemist shops, patients often share medicines with other members of the family — a serious hazard as infections differ from patient to patient.

Dr Chudgar, for instance, recalled a case where a patient used the eye drops prescribed by the doctor for another relative. Over time, she started losing her vision.

The most common side-effect of overusing steroid eye drops is cataract and glaucoma, but they could also cause ulceration (ulcer-like formations) in the corneas.

Ophthalmologists say people who use contact lenses are the most vulnerable as they often suffer from mild irritations in the eye and treat themselves with eye drops.

Take the case of Saumeet Bhandare (name changed) who suffered an eye infection after wearing lenses for long hours while travelling by air. Instead of visiting a doctor, he picked up eye drops from a local chemist.

“He ended up with a pseudomonas infection (a severe eye infection that damages vision),” said Dr Himanshu Mehta, ophthalmologist, Lilavati hospital, Bandra. Bhandare fortunately regained vision after treatment.

“If there was any more delay in reaching the hospital, he would have gone completely blind in one eye,” said Dr Mehta.

From mild ear infection to hearing loss

Bhayandar resident Neelam Chenvankar’s mild fungal ear infection turned severe with hearing loss when she self-medicated with drops that she bought from her chemist.

“Even after regularly putting the drops, the pain increased instead of subsiding,” said Chenvankar, 45, who works in a private company.

Chenvankar's doctor informed her that she was using the wrong drops for her ear infection, which only aggravated it.

“She used the drops for many days without consulting the doctors. We see many such patients who self-medicate with drops and come with severe side-effects,” said Dr Sanjay Helale, ENT surgeon, Kohinoor hospital, Kurla.

“This patient had been using two to three different types of drops, which were actually made to remove wax.”

vinay mohanty

take care of your home when you are for away

Real estate is possibly the most popular investment vehicle if you are a non-resident Indian (NRI). But since it is just that, an investment, the property needs looking after as you, the owner, are far away in your country of residence.

You may visit once a year but you find that this brief visit is simply not enough to deal with real estate issues such as maintenance, renting, utility


bills and property taxes. You must have wished that the professional property management firms you see working so well in the developed countries could set up shop in India as well. Your wishes seem to be coming true if recent trends are any indication.

There are a host of property management firms that have set up shop in the country and offer a variety of services. Here’s a look at who they are, what are the services that they provide and what are the costs involved.

Services available and providers

There are property management companies that have set up shops and provide a variety of services. These companies provide services such as supervising repair works, housekeeping, visiting property for inspections and also coordinating property tax payments, updating legal documents and so on. Along with this they will send you pictures of your property on periodic basis.

Take the case of Bangalore-based Homewell Developers Pvt. Ltd. You’ll need to pay an annual membership of Rs.30,000 per flat, no matter how big, to Homewell. This Rs.30,000 gets you services for a year including housekeeping, paying of bills, pest control, painting, and plumbing and so on. Along with this, you will have to pay the vendors for the costs that they incur, such as employee costs and costs of equipment.

The property management firms have tied up with vendors (those that will do work such as cleaning, plumbing and so on) who provide these various services. So you can either pay this amount to the property management company (via cheques) or even pay it directly to vendors.

Chennai Property Management, another firm offering the service, charges a minimum yearly fee (for a 2 bedroom-hall-kitchen apartment with monthly housekeeping and paying of monthly utility bills and taxes) of Rs.17,000. Along with this, you will have to pay the vendors that carry out the services. For instance, you will have to shell out Rs.700 for a cleaning session (Rs.600 which is the fee for the worker who can be a cleaner and Rs.100 for food and the travel of that person).

Aukeva Inc., a San Francisco- and Delhi-based property management firm will charge you a yearly fee of between Rs.10,000 and Rs.2 lakh along with the actuals. The charge will depend on the size, location and the services that you avail. The charges will also depend on the location, size of the property and the bouquet of services that the customer will choose.

The second entity that can help you is your own developer. However, not all developers have an in-house property management firm. What they do is point you in the direction of a fee-for service provider not linked to the builder or can take over the task of the service. “We provide help in getting residents in touch with such firms and for this we do not charge anything,” says R. Karthik, chief marketing officer, Lodha Group. Godrej Properties Ltd, though, do not offer property management services, they can guide to the firms that offer these services.

Others such as the Kerala-based developer Abad Properties has a separate property management division. A spokesperson for the company said that they offer these services especially for NRIs. These services are not just available for their clients, but those who own properties with other developers as well as those with independent villas. They offer housekeeping services and you can choose to get it done weekly, monthly or even just right before you come for your visit.

For instance, if you want monthly housekeeping service for your three bedroom-hall-kitchen set, Abad will charge you a fee of Rs.1,000 a month. And for a villa, they will charge you Rs.2,000. For services such as repair work or cleaning of swimming pools, you will have to pay Abad the employee cost along with the cost of equipment and an additional 10-15% of this total amount. Another developer that offers property management is Prestige Estate Projects Ltd.

The paperwork

When you enlist for these services, you’ll need an identity proof that shows that you own the property (it could be a sales deed). “You will then have to sign a service agreement with the property management firm. You will also have to give us a set of keys of the property,” says Radhika Bahadur, founder, Aukeva Inc.

You needn’t have to meet the property management firm in person or even send a power of attorney. The agreement can be signed via email as well, says Bahadur. Since property management companies help you in paying property taxes, the property tax papers is something that they will require. You will also have to introduce the property managers to your society’s association president.

However, keep in mind to avail services of a trusted property management firm as there are many smaller firms that provide these services.

Do your groundwork before enlisting their services. Ask these firms if they can give you contact details of their existing clients to get a feedback of the quality of services.


vinay mohanty

how much do you know your insurance bonus?

Your insurance policy is just not for saving tax. The bonus that accrues on your policy can also help you maximise your wealth.

Bonus is a very common term in insurance agreements. Even, an insurance seeker always has a tendency to find out a policy which offers more bonuses. A bonus is a reward or an extra amount which an individual gets over and above the sum invested (base amount) in the insurance


policy. In insurance industry, bonuses can only be associated with life insurance products.

A bonus is generally accrued by the insurance provider every year but it is only provided to the insured or the nominees of the insured in the event of maturity of the policy or in case of unfortunate death of the insured.

A bonus is not paid apart from these two situations under a life insurance policy contract.

Under life insurance policy contract, insurer provides protection and coverage from several risks for which insured has to pay insurance premium to the insurer. Insurance premium is dependent on many factors like the age of the person, coverage provided by the policy and tenure of the coverage.

In India, insurance products are just considered as an instrument to save tax but you must understand its importance as a wealth maximisation instrument as well.

A premium paid by policyholders to the insurance companies generates revenue for a policyholder acting as a source of bonuses as well.

The premiums paid by policyholders are pooled within life insurance company’s fund and then invested in order to pay out claims and bonuses. Bonuses are offered on traditional plans which are built into the plan structure. But as more and more innovative products are introduced in the market, people have started expecting to reap more benefits from life insurance products.

Unit linked insurance plan is one such insurance product which provides dual benefit of insurance and investment. Money parked in this form of life insurance not only protects from risks but also act as a source of wealth maximisation.

The insurance premium is pooled by the insurance company and invested into government securities including debt instruments and equity markets in order to generate revenues for the investor. Generally, the insurance companies invest funds as per predefined structures.

Here are few forms of bonuses offered by insurance companies:

Simple reversionary bonus (SRB)

This type of bonus is the basic form of bonus provided with every traditional plan. This type of bonus is only calculated on the sum assured. It is generally declared annually and is accrued to be paid out at a time of maturity or the claim.

Compound reversionary bonus (CRB)

As the name suggests, the main difference between simple bonus and compound bonus is the compounding factor.

Compound reversionary bonus is calculated as a percentage of sum assured and is calculated taking into account previously accrued bonuses. The bonus of each and every year is added to the sum assured and next subsequent bonuses are calculated on the added amount.

Terminal bonus

Terminal bonus is not a necessary form of bonus provided by the insurance company and is provided at sole discretion of the provider.

This form of bonus is provided at the time of maturity or death of the life insured. It may be given to the policyholder after staying in the policy for a specific amount of time.

Interim bonus

Interim bonus is paid by the insurance company for a period falling between two annual declaration dates. It is paid for the policies that mature or result in a death claim in between two bonus declaration dates.

Interim bonus is added on a pro-rata basis using interim rates declared by the company.

Cash bonus

Cash bonus is the only bonus paid on yearly basis to the policyholder. This form of bonus is generally given in cash and is paid at the end of the year.

Insurance companies lure perspective insurance seekers with lot of bonus promises but an individual must compare various policies so as to buy the policy meeting all your requirements.

One can compare life insurance policies with the help of insurance aggregators as they provide comparison tools and calculators to perform comparisons. Comparison of insurance policies not only help you buy insurance policies with higher bonus values but also help you buy policies within your budgets as well.

vinay mohanty

the career that pay

(IRDA) has reduced the pass percentage to 35% with immediate effect from 50%

In a bid to increase the number of candidates qualifying as an insurance agents, the Insurance Regulatory and Development Authority (IRDA) has reduced the pass percentage to 35% with immediate effect. Earlier, a candidate had to score a minimum of 50 % marks for qualifying in the pre-recruitment agent’s examination.

The IRDA has been receiving representations from various stakeholders expressing the practical difficulties involved in the recruitment of insurance agents.

Among other reasons, the mandated higher benchmark of 50% marks is identified as major reason contributing to reduction in agency force in the country, said a circular from IRDA.

Therefore IRDA said that considering the fact that the agents are under direct supervision of marketing officials of insurers who train them on the job continuously, it has decided to reduce the pass percentage benchmark.

In 2011, IRDA conducted a thorough review of the existing life insurance agent licensing qualification and decided to use the expertise of Chartered Insurance Institute (CII), London, in enhancing the existing IC33 ‘License to practice’ – the qualification for pre-recruitment examination for life insurance agents conducted by the Insurance Institute of India (III).

The syllabus introduced was challenging in its scope and depth. It did not encourage agents to merely memorise facts and figures, but also tested their understanding of learning, and ability to apply it in a wide range of practical real-life situations.

As a result, very few candidates were able to clear agent’s examination leading to significant drop in the number of insurance agents in the industry.

According to IRDA annual report FY’12, the year 2011-12 witnessed 10.63% decrease in the number of individual agents. The number has gone down to 26.39 lakh as on 31 March 2011, to 23.59 lakh as on 31 March 2012. While total number of agents appointed by life insurers was 7.14 lakh, the number of agents terminated was as high as 9.95 lakh.

The scenario was worse for private life insurers compared to Life Insurance Corporation of India (LIC). While private insurers appointed 3.68 lakh agents, 5.89 lakh agents were terminated. On the other hand, in case of LIC, 4.04 lakh agents were terminated, while it appointed 3.45 lakh agents.

Insurers say that agent examination had become more caselet oriented with application of knowledge to ensure that only those who can apply their knowledge are able to clear the exams. Bringing down the minimum pass percentage will ensure that more number of students qualify as agents.
vinay mohanty

your dream be bigger then your fears


vinay mohanty

what type of losses cover in insurance?


Losses covered in Insurance –
Financial protection to family after insured person’s death.
Insured repayment of debt after the death of insured debtor.
Protection against contingent liabilities
Financial protection to the family of employee after his or her death while service.
Protection against the uncertain situation after the death of partner or co-shareholder in a business.
Financial backup while loss in business or entity
Protection against uncertain health or medical expenses.
Protection against theft or fire or natural hazards.
Protection against legal affairs or law suits.
Protection against physical disability
Protection of vehicle against accidental or theft losses.
vinay mohanty

dear friends fast forward your business


vinay mohanty

what heppens after 30 9 2013 to lic agents?

Dear friends,

good morning all. As per new IRDA directions, our lic is going to close all existing plans by 30-09-2013 and

new plans will be introduced from 01-10-2013.

I request you all to comment on this. what is going to happen and what is the future of lic and lic agent.

With kind regards,

vinay mohanty

HDFC Standard Life tops unfair trade practices complaint chart

By PTI | 23 Apr, 2013, 06.00PM IST

NEW DELHI: Leading private life insurers HDFC Standard Life, Bajaj Allianz and Birla Sun Life top the list of firms against whom consumers have have filed complaints with sectoral regulator Irda for indulging in unfair business practices.

The other major companies against whom large number of complaints for making false lucrative offers to sell policies have been filed include ICICI Prudential and Reliance Life,Finance Minister P Chidambaram informed the Rajya Sabha in a written reply.

As compared to their private counterparts, the number of unfair business practice complaints filed against public sector behemoth LIC was significantly less during 2012-13.

Insurance regulator Irda, Chidambaram said, "based on its own enquiries, levies penalty on insurance companies wherever a case of unfair business practice is established".

Based on the data by the Finance Minister, the total number of unfair business practice complaints have shot up to 1.68 lakh in 2012-13, from about 1 lakh a year ago.

During the year, the number of complaints filed against HDFC Standard Life during 2012-13 stood at 33,813 followed by Bajaj Allianz (21,745), Birla Sun Life (21,651), ICICI Prudential Life (16,891) and Reliance Life (16,401).

In case of LIC, which is the largest insurance company in the country, only 2,538 complaints regarding unfair business practice were received by Irda.

vinay mohanty

How to Lock Your Car and Why!

Subject:Car Locking - well worth knowing.

How to Lock Your Car and Why!

"I locked my car. As I walked away I heard my car door unlock''.
I went back and locked my car again three times.

Each time, as soon as I started to walk away, I could hear it unlock again!! Naturally alarmed, I looked around and there were two men sitting in a car next to the Store.

They were obviously watching me intently, and there seemed no doubt they were somehow involved in this very weird situation.

I quickly abandoned my errand, jumped into my car and sped away.

I went straight to the police station, told them what had happened, and found out I was part of a new, and very successful, scheme being used to gain entry into parked cars.

Two weeks later, my friend's son had a similar experience....While travelling, he stopped at a motorway service area to use the toilet.

When he came out to his car less than 5 minutes later, someone had managed to get into his car and had stolen his mobile phone, laptop computer, sat-nav, briefcase and other belongings.

He called the police and since there were no signs of his car having been broken into, the police told him he had probably been a victim of the latest robbery tactic – there is a device that robbers are using now to clone your security code when you lock your doors on your car using your remote locking device.

They sit a distance away and watch for their next victim. They know you are going inside the Store, restaurant, or whatever and that they now have a few minutes to steal and run.

* The police officer said always to lock your car manually with the key when parking in a public area. That way if there is someone sitting in a car nearby watching for their next victim, it will not be you.

When you lock up with the key upon exiting, it does not send the security code, but if you walk away and use the remote button, it sends the code through the airwaves where it can be easily intercepted by the device.

This is very real. Be aware of what you just read and please pass this information on.

Look how many times we all lock our doors with our remote just to be sure we remembered to lock them -- and bingo, someone has our code...and potentially whatever is in our car."

Please share with everyone you know in the hope that we can frustrate these thieves.
vinay mohanty

only i can change my life

You will make more friends in a week by getting yourself interested in other people than you can in a year by trying to get other people interested in you.
vinay mohanty

make imposible as posible

You will never leave where you are, until you decide where you'd rather be.
vinay mohanty

Success is 99% failure. - Soichiro Honda

1. Unless you walk out into the unknown, the odds of making a profound difference in your life are pretty low.
2. You gain strength, courage and confidence by every experience in which you really stop to look fear in the face...You must do the thing you think you cannot do.
- Eleanor Roosevelt
3. Good ideas are common - what's uncommon are people who will work hard enough to bring them about.
- Ashleigh Brilliant
4. If your work is becoming uninteresting, so are you. Work is an inanimate thing and can be made lively and interesting only by injecting yourself into it. Your job is only as big as you are.
- George C. Hubbs
5. Formal education will make you a living; self-education will make you a fortune.
- Jim Rohn
6. The wise man puts himself last and finds himself first.
- Lao Tsu

7. It is not your customer's job to remember you. It is your obligation and responsibility to make sure they don't have the chance to forget you.
- Patricia Fripp

8. Here is a simple but powerful rule … always give people more than they expect to get.
- Nelson Boswell


9. Obstacles don't have to stop you. If you run into a wall, don't turn around and give up. Figure out how to climb it, go through it, or work around it.
- Michael Jordan

10. To be what we are, and to become what we are capable of becoming, is the only end of life.
- Robert Louis Stevenson

11. Stop selling. Start helping.
- Zig Ziglar

12. success is after 99% failure

vinay mohanty

Zonal club convention at vizag 24/4/2013


LIAFI hearty welcomes to visakhapatnam 

to all Zonal club members participants,

24th, April 2013 NOVATEL HOTEL, BEACH ROAD, VISAKHAPATNAM

vinay mohanty

DONT BE A DEPENDANT

DON'T BE A DEPENDANT

BE  A INDEPENDENT AND

SUCCESSES COMES TO YOU

vinay mohanty

dream well, dream big don't allow it to get washed away

vinay mohanty

world no 1 agent earns 7crores plus as income


Gideon du Plessis failed in the 10th standard and never went to college. He is today the highest earning insurance agent in the world, with annual commissions amounting to Rs 7 crore (Rs 70 million) plus.


A record he has maintained over the last 12-14 years, selling 700 policies yearly. Labelled by the Million Dollar Round Table -- an international association of leading life insurance and financial services professionals -- as "the most productive agent in the world", Plessis' efforts means an average daily accretion of two risk covers for his insurance company Old Mutual Plc.

Looking at the India [ Images ]n scenario, the largest life player, Life Insurance Corporation of India boasts of its highest selling agent earning a commission of Rs 2.1 crore (Rs 21 million) in 2003.

The highest average is in the region of Rs 1-1.5 crore (Rs 10-15 million), said LIC [ Get Quote ] sources.

So what is Plessis' secret of success? He lives by 12 mantras  that have taken him so far since he got into the insurance selling profession 23 years back.

Based in Cape Town (South Africa [ Images ]), Plessis starts his week Monday morning at 5:30. He flies 2,000 km to meet his clients in various parts of South Africa, works 17 hours at a stretch -- doing business across office desks and/or over a cup of tea in the comfort of clients' homes, encounters at least six to eight persons daily, and then relaxes over the weekends playing golf.

But ask Plessis as to how he sells insurance? And he'll tell you he does not. "People buy people, not policies," he told Business Standard in an exclusive interview.

Insurance continues to be sold and not bought. So the idea is to ask questions and more questions, collect all the information about the client and then go back to him/her with a solution. You are not selling anything to anybody ever, but rather providing a solution to meet his/her needs, said Plessis.

Plessis was on a tour of India last week, educating the agency force of OM Kotak Mahindra Life, Old Mutual's joint venture in the country, on succeeding in the insurance business.

"It is important to pay attention to detail. Flowers on your client's birthday, condolences when the secretary's distant relative passes away. The personal touch matters and goes a long way," he advised local agents, who were more keen to learn if he sat on the chair or on the sofa when doing business.

Since the age of 10, Plessis wanted to earn money with his mouth. Aiming to be a teacher, but having failed in English, Plessis decided that salesmanship was where his talent lies. Plessis started out as a postman, then became a bank clerk visiting farms to sell products, before he was picked up by Old Mutual to sell insurance policies. Since then, Plessis has never looked back.

Plessis does not only target the high networth individual. Rather, 60 per cent of his clients are from the middle class.

Plessis' mantras
See at least 6-8 people daily
Selling is not telling: ask a lot of questions & go back with a solution.
Attend to details
Go soft in life
Delegate staff
People buy people, not policies
Educate yourself properly
Time management
Wake up to achieve what you want
Elephants don't bite, mosquitoes do
Desire
Enthusiasm

vinay mohanty

we are leaders of singapure not looters of singapure

vinay mohanty

హౌ లైఫ్ ఇన్సురన్సు వర్క్స్ అవుట్ తో యువర్ ఫ్యామిలీ ?

హౌ లైఫ్ ఇన్సురన్సు వర్క్స్ అవుట్ తో యువర్ ఫ్యామిలీ ?
1. ఫర్ కంట్రీ సెక్యూరిటీ వే నీద ఆర్మీ /నవి /ఎయిర్ ఫోర్సు .
2. ఫర్ ఇంటర్నల్ లా అండ్ ఆర్డర్ వే నీద పోలీస్
3. ఫర్ వాటర్ , అగ్రికల్చర్ అండ్ పవర్ వే నీద హైడ్రో ప్రాజెక్ట్స్ .
4. ఫర్ హెల్త్ సిక్నెస్ /సుఫ్ఫెరింగ్స్ వే నీద డాక్టర్స్ /హాస్పిటల్ .
5. ఫర్ క్నౌలెద్గే వే నీద ఎడ్యుకేషన్ /స్కూల్
6. ఫర్ రైన్ /సన్ వే నీద ఉమ్బ్రెల్ల .
7. ఫర్ ఫుడ్ వే నీద అగ్రికల్చర్ /మనీ /జాబు
8. ఫోర ఓల్డ్ ఏజ్ వే వన్త పెన్షన్ /ఓల్డ్ ఏజ్ ఫండ్
9. ఫో ర పవర్ ఫెయిల్యూర్ అత్ హోం వే నీద ఉపస్ .
10. ఫర్ ఆక్సిడెంట్ /ఊనెక్ష్పెచ్తెద్ డెత్ వే నీద ఇన్సురన్సు
11. ఈన్సురంచె మనీ విల్ కంపెంసతే ఫర్ చిల్ద్రెన్ ఎడ్యుకేషన్ ,
మ్యారేజ్ , ఫమిల్య్ ఫండ్ , లోన్ రేపయ్మేంట్ , హెల్త్ ఏక్ష్పెన్సెస్ .
12. ఇన్సురన్సు ఇస్ అ దమే ఫర్ ది ఫమిల్య్ , లికె (ఆర్మీ , డాక్టర్ ,
పోలీస్ , ప్రాజెక్ట్స్ తో కంట్రీ ), తో సేఫ్ గౌర్డ్ ది ఫ్యామిలీ మెంబెర్స్
అండ్ హిస్ /హర్ సెల్ఫ్ ఇన్ దిసబ్లేడ్ , ఇన్ అల్ ఎక్ష్పెన్సెస్ అండ్ నీద్స్
13. సో ప్లాన్ ఫో ర లైఫ్ ఈన్సురంచె , హెల్త్ అండ్ జనరల్ ఇన్సురంచె
14. ఈన్సురంచె ఇస్ అ బిగ్ co-ఒపెరతివే సొసైటీ , అల్ ది మెంబెర్స్ విల్
చొంత్రిబుతె మనీ తో సేఫ్ గౌర్డ్ యువర్ ఫమిల్య్
15. Call/SMS/mail us 9396258548, 9848258548, 2520511,
vinay60@sify.కం
vinay mohanty

How LIC insurance will works out to your family


vinay mohanty

LIAFI EC meeting at VIZAG Andrapradesh

LIAFI Excutive committee meeting will be held at visakhapatnam on 27th and 28th May 2013, time 11AM of 27th may 2013 and venue: platinum jubilee gust house, Nr: Distance educatuon building, Opp:AndhraUniversity out gate, Chinnawaltair road, visakhapatnam

contact persons - Mr venu (divisional president)09440913644, Tirumalarao 9848456957, sastry 8374341114, murty 9246623012

all all india liafi EC members are requested to attend the meeting and make the meeting grand success

vinay mohanty
chairman IT LIAFI

modi for modern india

v

happ holli to all liafians


vinay mohanty

India leads world in road deaths


India leads world in road deaths: WHO

NEW DELHI: In a dubious distinction for the country, the World Health Organization has revealed in its first ever Global Status Report on Road Safety that more people die in road accidents in India than anywhere else in the world,
The statistics for India are chilling. At least 13 people die every hour in road accidents in the country, the latest report of the National Crime Records Bureau reveals. In 2012, 2.14 lakh people in India lost their lives in road mishaps - that's significantly higher than the 2011 road death figures

Road deaths in India registered a sharp 6.1% rise, However, road safety experts say the real numbers could be higher since many of these accident cases are not even reported. "There is no estimate of how many injured in road accidents die a few hours or days after the accident," points out Rohit Baluja, member of the UN Road Safety Collaboration and Commission.

As per 2012 Railway survey more than 2400 people in tamilnadu died in Rail Accident

( Crossing Railway Line )and more than 500 people died whil using cell phone in crosing

the railway line

AN APPEAL

What your family will do if you are a victim in that accidents?

Any time any thing can take place to any one among us.

Either today or tomorrow or any other day but every one will get their death

certificate if not the birth certificate. For sure.

The truth is:

No one is exceptional and everyone has to leave this place, people, property,

belongings, affections and emotions.


What is the Immediate Action Required?

Question Yourself.. Am I Exceptional?

What would have happened to my family if I am also one among them who got

their death certificate?

Solution !!!

"Insure yourself Today" as per your requirements. Calculate your insurance

requirement as per the scientific methods. If you are married and have

dependents, if you are not married and have dependents still every one has to

insure..


Please Note - ( You can take advice from any of your financial advisor/Agents,

and this is not a obligation mail for selling insurance)

Only for one reason.. To Leave your dependants to live with assurance of

coming years in your absence.

We, Insurance Professionals have lost many lives of customers across the

country and feel so bad to give a very small amounts of death claims to the

widow. It hurts to give.

We know that family can not survive the remaining of life but no alternative,

the bread winner of the family has never thought what happens to my family

if today is my last day in life.

An Appeal:

No matter whether you are staying in metros or in villages, No ones life is secure.

If you cant do many things for the society,

At least do something for your family.


Respect Insurance Professionals who really care for you and your family. They

come to you to build happiness and prosperity in your family, when they visit

next time, Help them to Help others by referring your friends names

who needs immediate insurance and who has not insured till now.


No one wants to see, a widow of our friend comes to our

house day after day for financial support.


If you help your friend to Insure today, tomorrow you need not feel that you

could have advised him to insure."YOU NEED NOT BE AN AUTHORISED

INSURANCE PROFESSIONAL" to be a part of this DIVINE ACTIVITY of insuring others.

"we have to insure not because we may die, but for our dependants who will

live"

"Let us build a better society for us and for our coming generations"

Mail us, we can help you

(Kindly send this to all your friends, family members and whom you really care)
vinay mohanty

LIAFI congrats to Rajeev lohia for his victory


LIAFI congrats to Rajeev lohia for his victory

Ex-agent wins 10-yr battle against LIC for Rs44Lakhs dues //times of india 17-3-2013 kolkatta

kOLKATA: A star agent of the Life Insurance Corporation of India serves the insurer for 27 years, sells so many policies that at one point he is exempted from generating the minimum quantum of business required, and then quits to join another insurance firm as a regional manager. Can the LIC withhold renewal commission that is due to him for joining a rival firm?  In a judgment that has a bearing on the careers of nearly three million LIC agents across the country, the Calcutta high court has ruled that it can't.
 Former LIC agent Rajeev Lohia from Kolkata fought a legal battle against LIC for nearly 10 years and got a ruling in his favour last October. LIC was directed by the division bench of Justice Kalyan Jyoti Sengupta and Justice Asim Kumar Mondal to pay Lohia his entire dues within three months. The insurer, however, didn't do so and when Lohia moved a contempt petition against the company in January this year, it prayed for time to move a Special Leave Petition (SLP) in the Supreme Court. The Supreme Court admitted the SLP on March 1 on condition that LIC deposit Rs 44 lakh that was due to Lohia till 2011 with the court registry.
 Son of an LIC agent, Lohia joined the profession in 1975, when he was barely 18 years old. "I would get up at 4 am, attend classes at St Xavier's College till 9.30 am then go around 'cold canvassing'. This meant knocking on the doors of people I didn't know and asking them if they required a policy. I remember when I met my first client and produced my college identity card to prove that I wasn't a fraud, the man told me his mother, a nominee to his policy, had died 10 years ago. I told him that these are the small issues that can cause problems later on. He was my first client. After my rounds, I would attend management classes in the evenings," said Lohia, who went on to become the youngest Chairman's Club member ever.
 In his career spanning 27 years, Lohia claims to have sold 2,764 policies to about 1,000 people. The premium per year for these policies amounts to Rs 2.25 crore. "My father would get magazines on the insurance industry from the US. These were of great help. From there we came to know of the Million Dollar Round Table (MDRT) and started communicating with it. The MDRT used the purchase price parity index to fix a barrier. Any agent who wished to qualify for MDRT needed to earn a commission of Rs 1.25 lakh per year. This was in 1985. For 15 years, I remained a life and qualifying member of MDRT and attended 12 conferences in the US and Canada. In 1986, for the first time, the Indian flag was hoisted at a MDRT meet due to our efforts," Lohia said.
 On March 7, 2002, he resigned from LIC to join a private firm as regional manager. His agent's licence was also due to expire on March 31 that year. The very next day, he was asked by his branch manager to furnish the name and address of the private firm that he had joined. Lohia refused to do so as he had already resigned and the principal-agent relationship between LIC and him had ceased to exist. On April 22, 2002, he received a show-cause notice for alleged misconduct and LIC threatened to terminate his agency. Lohia replied that he had already resigned and his agency stood terminated. On August 16, 2002, he was informed that the renewal commission due to him would be withheld as penalty for termination of agency. The former agent preferred a departmental appeal but nothing came of it.
 "I had never expected such a reaction from the company that I had served with such commitment. This was when I realized that the company treats agents as bonded labourers who have no rights to seek better opportunities in life. I went to court, not only for myself but for the three million LIC agents across the country. Under law, even after an agent's death, his next to kin are eligible to receive the renewal commission. By withholding my commission, was LIC trying to establish that agents would rather die than join other companies?" Lohia said.
 On August 13, 2003, he moved a writ petition in the high court. He told the court that the renewal commission can't be withheld save for commission of fraud. In his case, termination of agency was not due to fraud, Lohia submitted. The court then wanted to know from LIC how much the company owed the former agent. The company submitted that the renewal commission due till June, 2011, was excess of Rs 44 lakh. A further Rs 32 lakh was also due apart from Rs 1 lakh as gratuity.
 According to the judges, someone's right can't be taken away on 'mere presumption or assumption'. "We hold that the petitioner-appellant is entitled to get all benefits of renewal commission as well as gratuity. We accordingly direct the respondent Corporation to quantify the same and make payment and we permit three months time to do so," the court ordered.
LIAFI …. LIAFI …. LIAFI …. .LIAFI....  
We are for agents, we live for agents
LIAFI …. LIAFI …. LIAFI …. LIAFI …. 


vinay mohanty

LIAFI great achivement


premiume       Maximum      commsision/remunaration    
paying term    in any form as % of premiume    
  1st year 2&3rd year subsequent year
5 15 7.5/5* 5
6 18 7.5/5* 5
7 21 7.5/5* 5
8 24 7.5/5* 5
9 27 7.5/5* 5
10 30 7.5/5* 5
11 33/30 * 7.5/5* 5
12years 35/30* 7.5/5* 5
or more      
new commission rates as per IRDA notification 
vinay mohanty

latest traditional product guideline IRDA

In the latest traditional product guidelines, the Insurance Regulatory and Development Authority (IRDA) have called for non-linked variable insurance products (index-linked products) to be treated at par with unit-linked products (ULIPs). The insurers have been given time till June 30 2013 to re-file group products and September 30, 2013 for individual products re-filing.

The ceiling for first year commissions has been put at 15% for the first year for a 5 year term, 30% for 10 years and 35% for 12 years or more (40% for insurers aged less than 10 years). If the polices are procured by direct marketing no commission will be allowed for direct marketing, IRDA stated.

The minimum guaranteed surrender value would be 30% of the total premiums paid less any survival benefits paid, if policy is surrendered in the second and third year. If surrendered in the fourth year, it would be 70% of the total premiums paid less any survival benefits already paid. If surrendered during the fifth to the seventh policy year, it would be 90% of total premiums paid, less any survival benefits already paid,” the norms said. The surrender value beyond the seventh year would need to be filed by the insurer under the File & Use for clearance.

IRDA fixed the minimum death benefit at highest of 125% of the single premium or minimum guaranteed sum assured on maturity or any absolute amount to be paid on death, for single premium products. For other products, it will be highest of 10 times the annualised premium or 105% of all premiums paid on date on death, or minimum guaranteed sum assured on maturity or any absolute amount to be paid on death.
Posted on March 7, 2013 by Akanksha

BJP PM candidate Narendra modi


Dr. Manmohan Singh's government is the most corrupt union government since independence. It is not a coalition government but is indeed a coalition of the corrupt," the BJP resolution said.


"The UPA is leaving a legacy of 'insecure India' and 'suffering India'. India needs to be redeemed by the NDA under the leadership of the BJP. It is time to awaken the country, expand the NDA and generate a hope for decisive change, whenever election is held," the resolution said.

It also called for expansion of the National Democratic Alliance (NDA).
gandhis hattao bharatmaa ko bachayo our next PM narendra modi

jay maa bharat maa,  jai jai bharat maata, jai jai bharat vassi, jai hindustan

Bank KYC Enough for Buying Insurance Policies

Finance minister, P. Chidambaram in the budget said that Know Your Customer (KYC) norms of banks will be sufficient to acquire insurance policies. This will be eligible for both life and general insurance policies.

In other words, a person already holding a bank account will not be require to give any more documents while buying an insurance policy.

Rationale behind this move is that if the customer holds a bank account, it means the person has already submitted his identity and address proof, the key elements to satisfy the rules of KYC norms.

The person will not be asked for any more documents, irrespective of the bank he holds the account in. A customer who wants to buy an insurance policy has to merely submit a certificate from the bank (in which he holds an account), stating he is an existing customer and has satisfied the KYC rules.

Common KYC for banks and insurance policies will help in faster issuance of policies, make the process simple and reduce frauds as well. This will also increase insurance penetration, especially in Tier II and Tier III cities.

However, general insurance companies might insist on a separate KYC in some cases. They might need the potential customer to undergo additional KYC, if their insurance premium exceeds Rs 1 lakh. This can be applicable for fire, marine and householder policies, where premiums are usually on the higher side.
vinay mohanty

fiuture days will Dark days for US

vinay mohanty

DEAR AGENT FRIENDS


DEAR AGENT  FRIENDS,

  PL DONT ENTER EMAIL IDS OF UR CLIENTS IN LIC RCT DETAILS.
LIC IS STEALING THOSE IDS AND GIVING THEM TO LIC DIRECT MARKETING.
FEW DAYS BACK I HV ENTERED MY EMAIL ID TO MY OWN RCT-- I HV STARTED
GETTING REGULAR EMAILS FOR BUYING NEW POLICIES FROM DIRECT MARKETING
--WE HV TO TAKE THIS MATTER WITH LIC MANAGEMENT.
ASK THEM TO STOP CHEATING THE AGENTS

some of our friends writen this letter but it is true

jago sansad jago


vinay mohanty

Government propose to amend the Insurance Act 1938


You all are aware that the Government and IRDA propose to amend the Insurance Act 1938 in the coming session of Parliament. These proposed amendments in the act will:


1. Stop payment of balance commission and gratuity to the widow of an agent, means the hereditary commission goes,


2. Powers of the Parliament to decide the rates at which commission to a life insurance agent of LIC as well as that of a private insurer have to be paid, will be transferred to IRDA. Means the rates of commission will be decided by IRDA.


3. Delete the provision of prohibition of stopping of payment of commission to insurance agents.


These amendments will dismantle the agency structure in India prepared after years of hard work and after spending hundreds of crores.


This will cause lakhs of crore loss to the Government in the form of premium not received which is being utilized for long term investment in the infrastructure development of the country. The story of mutual fund, PPF and General insurance is before us where in business has been badly reduced due to neglect of insurance advisors/agents.


Please recall the recent draconian suggestions made by Devendra Swaroop committee to stop payment of commission to us.


In the light of the above we have decided to launch nation wide agitation against these proposed amendments in the Insurance Act.


vinay mohanty

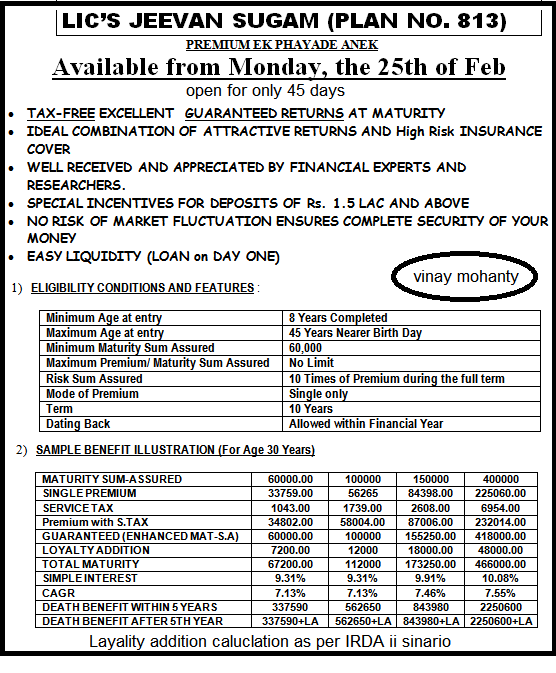
JEEVAN SUGAM 813 PLAN WILL LANCH 25Th FEB2013

rajnathsnigh and others assure they will do best

Our leaders met Mr. Rajnath Singh ji President BJP, Mr. Arun Jaitely Leader of Opposition Rajya Sabha, Smt. Sushma Swaraj, Leader of Opposition Lok Sabha and discussed about Insurance Bill.All leaders assure us that they will protect our interest.After that we met with Mr. Rajiv Takru (chief secy ministry of finance for financial matters) He also assure that he will do his best.

vinay mohanty

special medical report chart


vinay mohanty

agent can take3 agencis life/general/Health

NOW ANY insurance  AGENT CAN TAKE 1.ONE AGENCY OF GENERAL INSURANCE.  2.one AGENCY OF A HEALTH INSURANCE .and 3.one Lifeinsurance agency LETEST INFORMATION.
vinay mohanty

IRDA new chief TSVijayan


21 February 2013

T S Vijayan, former chairman of the Life Insurance Corporation of India (LIC) has taken over as chairman of the Insurance Regulatory and Development Authority (IRDA).

Vijayan, 60, takes over from J Hari Narayan who ended a five-year tenure on Wednesday.

The IRDA head is appointed for a term of five years or till the age of 65 years.

An IRDA statement said Vijayan has taken charge as its chairman today.It is a comeback for Vijayan who was demoted to managing director of LIC following charges of financial irregularities. He had also taken voluntary retirement in November 2012.

Vijayan, who was battling corruption allegations with regard to investment decisions made by LIC during his tenure, however, got a clean chit from the Central Bureau of Investigation (CBI) and the finance ministry.


http://www.domain-b.com/finance/insurance/irda/20130221_vijayan.html

vinay mohanty

Insurer’s Managed Funds to Touch Rs30 lakh crare Mark in 5 yrs: IRDA Chairman


The size of funds managed by insurers in the country is expected to reach whopping level of Rs 30 lakh crores in next five years, a jump of 70% from current level, outgoing Insurance Regulatory and Development Authority (IRDA) chairman J. Hari Narayan said.

He said that when the insurance industry was opened up in 2000, the total controlled fund was about Rs 1 lakh crores. It was Rs 8 lakh crores in 2008 and it is Rs 18 lakh crores now.

He also said that he is in favour of government’s view of hiking Foreign Direct Investment (FDI) limit in insurance sector to 49% from current 26%. This would lead to a substantial flow of funds in capital intensive sector. It is estimated that insurance sector will require at least Rs 30,000 crores in next five years to double its size.

vinay mohanty

The total investment corpus of LIC has touched Rs 14.8 lakh crores


The total investment corpus of Life Insurance Corporation of India (LIC) has touched Rs 14.8 lakh crores (provisional) as of 31 December 2013 as against Rs 13.49 lakh crores at the end of December 2012, registering a growth of 10% in first nine months of this fiscal.

Investment in government securities accounted for a major chunk in LIC’s investments with investments worth Rs 7.27 lakh crores. Housing and infrastructure investments stood at Rs 1.91 lakh crores. And the rest included investments in the corporate sector and project loans.

Central government securities contributed Rs 4.77 lakh crores, followed by state government and other government guaranteed marketable securities.

Among housing and infrastructure investments, LIC has maximum amount of investments in the power sector, contributing Rs 94,294 crores.

This was followed by housing with Rs 41,900 crores. Other areas in infrastructure included irrigation, road, bridges, port and telecom.

LIC is expecting to invest a total of Rs 2.4 lakh crores in bonds, equities and government securities in the current financial year.

In terms of performance of different distribution channels, out of the first premium income, Rs 1,486 crores came from the chief life insurance advisor. Bancassurance and alternative channels contributed Rs 870.63 crores and direct marketing contributed Rs 218 crores.

vinay mohanty

Agent freinds allert from this letter


vinay mohanty

ADHAR CAR AS ADDRESS FROOF& ID PROOF


vinay mohanty

Does FDI 49% benefit the common man?

Does this benefit the common man?
  

 This change does not benefit the common man, as he is the target for all insurance companies, whether Indian or foreign, who try to extract maximum business from the gullible public, who are carried away by the sweet talk and tall promises made by the insurance salesmen. In fact they are concerned more about their own commission rather than the welfare of the insured. Insurance business is one where there is rampant mis-selling and the insurance companies go scot free because of a number of conditions included in the policy in small print, but never communicated in advance.
  

 Our country has a low insurance density and every company selling the insurance feels that there is abundant scope to expand its operations and hence this proposal to increase FDI in insurance has been received with great applause by the industry. Only time alone will tell whether this irrational exuberance is justified considering the fact that there is political opposition to this move and this change requires approval of the Parliament.
  

 If and when this proposal becomes a law there is bound to be a great demand from foreign companies to enter our country because of the abundant opportunity provided by the large population and the growing per capita income of our people. During the last twelve years, if over 40 foreign companies have entered our country as joint venture partners, with the increased FDI cap, we may expect another 100 companies to come within the next twelve years. Unfortunately, some of our people are carried away by the foreign names and brands, and that there is a perception among our people that foreign companies are better than the home-grown companies. But the fact is that foreign companies are as bad as or as good as local companies, and insurance business, whether run by Indians or by foreigners has the same objective, as in all business, of maximizing returns to the owners even at the cost of the insured.
  
How to protect “aam aadmi” from exploitation by the insurance companies?  
                 

 It is abundantly clear that mere hiking the FDI cap to 49% does not in any way benefit the common man, unless it is accompanied by stringent regulations to protect the “aam aadmi” from exploitation.