plan a budget holiday overseas in newyear2013

Travel packages 

 A tour package, by its very nature, includes sightseeing tours, meals according to plans and airport transfers; everything is pre-arranged and pre-booked. And, you don’t miss important sightseeing destinations. In the case of group-travel packages, the prices may be lower. 

 However, many find such prearranged tours hectic, as one has to adhere to the plan of the tour operator/guide. This category of travellers may consider the FIT (free independent traveller) format, in which one has the choice and flexibility to choose sightseeing destinations. A FIT traveller can also choose the airline and the number of days he/she plans to spend at a particular destination. “In this case, travel expenses may rise 30 per cent, compared to a group holiday,” says Anand. 

Buying forex 

 Buying foreign exchange (forex) is another aspect of travel one has to consider carefully. Indian travellers can buy forex only from aReserve Bank of India (RBI)licensed company like Cox & Kings, and not from any foreign operator or portal. According to the Foreign Exchange Management Act, customers have to provide know-yourcustomer details and compliance documents for availing of this facility. One can take up to $10,000 (~5.50 lakh) of forex a year for personal use. 

 Though one can buy forex in cash from an RBI-licensed company and pay as and when required, carrying much cash isn’t advisable; the good old travellers’ cheque is a good alternative. If bought from HDFC Bank, it costs one per cent of the rupee value of the travellers’ cheque. For transactions of up to $500, the bank charges 0.75 per cent of the rupee value of the cheque. There’s also the option of prepaid travel cards. These can be loaded in India and used abroad. In this case, forex conversion charges would be applicable at the rate prevalent on the day of conversion. One can also use a rupee credit or debit card. Here, too, forex conversion charges would apply. 

 Flexi foreign exchange cards, or multicurrency cards, are also popular. These are loaded with more than one currency and can be used across countries. For instance, a card used across Europe in the euro currency can be used in the UK in pounds and in the US in dollars. For these cards, various currency rates are frozen at the time of the purchase and, therefore, one doesn’t need to worry about exchange rate fluctuations. 

 Bankers say if one plans to travel in December, he/she should buy forex now. One may also choose to buy and accumulate forex when the conversion rate is favourable. 

Choosing destination 

 Each holiday season offers both domestic and international options. On the domestic front, this time, western and southern regions such as the Andamans, Kerala, Goa and Rajasthan seem to be the favourites. Among international destinations, Southeast Asian regions such as Singapore, Malaysia, Thailand, Mauritius, Sri Lanka and Hong Kong-Macau are expected to be top draws. Thomas Cook’s Pai says the Philippines is also emerging as a viable new destination. It is good value for money, he adds. Compared with the US and the UK, one could save 35-40 per cent on tickets to that country. 

 Vishal Suri, deputy chief operating officer (tour operating), Kuoni India, says travellers are opting for breaks to places where prices are reasonable. “For Indians, Southeast Asia has always been a popular destination. The ease of securing visas, proximity and bargain-shopping have attracted Indians to the Far East. These destinations offer an opportunity to enjoy a three- to four-day break without much hassle and planning. On the domestic front, weekend packages for destinations at drivable distances have gained popularity as last-minute getaways,” he says.....................Source : Business Standard, Dated : 19th Nov. 2012, .

Super Mario (Investment) Rules


vinay mohanty

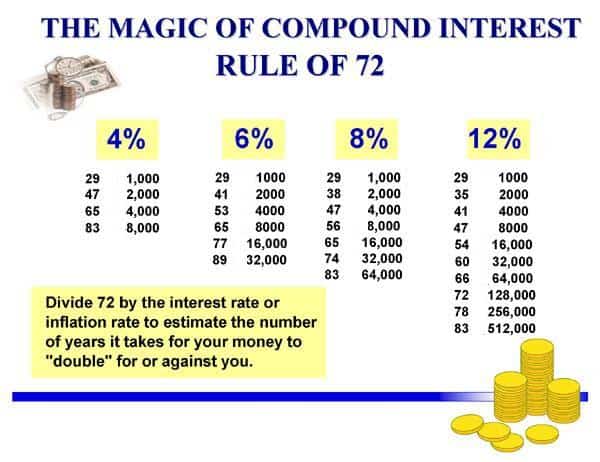
Rule of 72 (your money doubles in years)

vinay mohanty

HC Suggested IRDA to Set Up an Ombudsman for Policyholders


The Bombay High Court has suggested Insurance Regulatory and Development Authority (IRDA) to set up an ombudsman to address insurance related grievances of consumers.

The suggestion was made by the HC while hearing a Public Interest Litigation (PIL) pointing out the hardships being faced by medi-claim policyholders.

HC said that IRDA should consider setting up a forum or an ombudsman to look into the insurance related complaints, instead of dragging such cases to court or consumer forum.

In reply, IRDA said that draft guidelines have been prepared for settling of insurance claims and it will be placed before its board for consideration.

The PIL alleged that there were no standard guidelines to settle insurance claims and it was often done at the whims and fancies of Third Party Administrators (TPAs).

The PIL argued that, TPAs are not entitled to settle claims, but are found to be doing so in several cases. PIL also said that TPAs receives financial incentives to reduce claim ratios. And there was discrimination in settling insurance claims of individuals and that of corporate clients.

According to the PIL, problem began in July 2010, after public sector insurance companies, acting through TPAs, suddenly stopped offering cashless medi-claim benefits to consumers in top hospitals in the metros.

Earlier, over 1,500 hospitals use to offer cashless policy claims and there was no need for a patient to bother about paying cash while undergoing treatment as it would be settled by the insurance company.

The scheme was withdrawn as many irregularities were found in it.///   December 14, 2012 by Akanksha

Insurance as a social security tool

Insurance today has several implications for people from different economic backgrounds, however the basic concept of life insurance still remains the same and universal – to provide for unforeseen contingencies of death and disability of a working or earning member of the family.

Scope//////The term life insurance has financial as well as legal implications which need to be understood categorically before delving into the details of any polices.

Financial Implications: Life Insurance is a financial arrangement, which redistributes the costs of unexpected loss of life among the members of the pool. The pool is a collection of people facing common risks. All members contribute a fixed amount towards a pool called premium. In exchange for the premium payment, the person gets an assurance that a certain sum of money is to be paid to him or his nominees on the happening of the event insured against

Legal Implications: Life Insurance can be defined as a contract between two parties by which one party undertakes to make good or indemnify any financial loss suffered by other party, in consideration of a sum of money, on the happening of a specified event e.g. accident or death.

The scope of life insurance can be broadly stated under the following aspects:
 Insurance of life is a risk sharing instrument.
Life insurance is essentially a cooperative process in which a large number of people have to taken into the fold of the insuring agency and create a pool.
The value of the life has to be estimated in order to estimate the share of each individual in terms of premium.
 Payment contingency in case of life insurance is either at death or at the expiry of term either of which will definitely occur. Thus this contract is a contract of certainty.
 Insurance is not a form of gambling and it rather serves the purpose of eliminating uncertainty of financial situation by providing for unforeseen events. It additionally serves to increase the productivity of the community by eliminating worry and increasing initiative.
Insurance is not a form of charity as the sum assured is paid out against regular payment of stipulated premium.

A Tool for Social Security

Life insurance is one of the most effective tools of social security across the globe. In the absence of such a provision to the common people, the society will have no redressal for pitiful elderly masses, helpless widows, unprotected orphans; the factories will have to be scrapped after a fire; the houses will not be rebuilt after being struck by any calamity. With such events and more any economy cannot be stable leave alone the growth.

Our state, unlike the socialist or a developed capitalist society where states are responsible for the deprived and destitute, is ill-equipped to do so. Constitution of India has relevant clauses under the directive principles of the state policy. In article 41, it clearly dictates the state within its monetary and development capacity shall take effective measures to secure the elementary right of work, education, employment, health and any other undeserved want of every citizen.

Nevertheless, the failure of states is evident to all, with only a few schemes floated like the one for socially disadvantaged. Providing equal rights and opportunities for all is easier said than done. In the absence of the bread winner of the family there is little that the government or other social agencies can do to look after the welfare of those left behind. The same is true even in the most economically advanced nations.

Thus in order to ensure that the people left behind continue to enjoy the same privileges in society as before and thus stay with the mainstream, life insurance is a probably the best and only social security tool against unforeseen eventualities. It not only creates security but also goes ahead to foster a respect for savings to be able to secure future of the entire family.

A Tool for Independence

One has only three resources to fall back upon when a calamity strikes: savings, charity and insurance. Savings is a slow and tedious process as on average one saves only 10% of the earnings and they consume a life time to accumulate into something meaningful that can really come handy in a crisis. Additionally the exact amount that will be required is quite unpredictable making savings insufficient at most critical junctures. Charity on the other hand is demeaning and unreliable since it is completely at the mercy of the provider. Thus insurance remains the only and most viable option to fall back upon whenever crisis takes place.

Insurance is a product of ones farsightedness and present sacrifice for future anticipated gains and is thus commensurate with his self-respect and dignity. It encourages economic independence and is thus a tool of social security par excellence. The concept of life insurance has come a long way from its inception and today also provides a smart avenue for investment where the policy holder not only secures himself against unforeseen contingencies but is also able to create wealth over a period of time by letting the money paid towards insurance be invested in market oriented instruments.

How To Get Duplicate Copy Of Property Title, Shares, FD, Academic Certificates?

What do you do if you lose an important document, be it the school marksheet, property deed, or a bank deposit receipt? It can prove to be a nightmare since it can lead to financial loss and, if it is an original document, is liable to be misused. Even the loss of seemingly insignificant documents like school leaving certificates can pose a dilemma.

"The HR departments of companies may insist on such documents while verifying your background. If you don't have them, it can create difficulty for you while switching jobs," says Aakanksha Joshi, senior associate, Economic Laws Practice. The problem escalates when it comes to more important papers like those related to property or shares.

While the originals cannot be recreated, one can take appropriate steps to avoid fraud, says Rajesh Gupta, partner, SN Gupta & Co. Here's what you can do to mitigate your loss in case you lose the following documents.

Property title documents

The first step is to lodge a police complaint. Thereafter, issue a public notice in two leading newspapers, preferably in an English language and a vernacular one, stating the loss of document. Depending on the newspapers you choose, this will cost you Rs 3,000-30,000. Remember to keep a copy of the complaint as well as the press clippings with you as proof of loss.

To collect duplicate proof of property ownership, you can get a certified copy of the original sale deed from the office of the concerned sub-registrar of assurances, where the documents were registered. This should cost you less than Rs 500. You can also get copy of the relevant extract of land revenue records, where your ownership would have been recorded.

In case these documents have not been registered with the sub-registrar, say, where a buyer signs anagreement with the builder, a duplicate copy can be obtained from the office of the builder. However, make sure to put on record the loss of the original sale agreement with the builder.

If your bank misplaces or loses your property documents, it must notify you immediately. It should also provide a suitable indemnity to you and prospective buyers in case you sell your property. However, you will still have to lodge a police complaint and issue a public notice. The good news is that you can ask the bank to bear the associated costs.

In the case of share certificates of a housing society, the rules change slightly. To begin with, you can submit an application for duplicates, along with an indemnity bond, to your society.

The latter is a contract, wherein you promise to make good any loss that may arise in case the original instrument is presented. "Since some people mortgage originals as security with banks and then ask for duplicates, the society may ask you to give an undertaking that you have lost the originals in order to avoid fraud," says Gupta.

The society will then invite objections by affixing a notice to its notice board as well as through a notice in the newspaper. You may be asked to foot the associated costs, and some societies even expect you to assume complete responsibility for this task.

If there are no objections within a stipulated time frame—ranging from 15 days to one month, depending on the society—you will get your duplicate certificates for a fee of Rs 500-1,000.

Physical shares

 Here, too, you have to lodge a complaint with the police and publish a notice in two newspapers, stating that you have lost your certificates. The next step is to file for a perpetual and mandatory injunction. The former is a court order, which will restrain the company from accepting your lost share certificates in case somebody else tries to deposit them. Mandatory injunction is also a court order directing the company to issue duplicate certificates to you. While applying for a duplicate, you need to submit a copy of the police complaint and court injunction to the company, along with an indemnity bond and an undertaking that you have not sold your shares to a third party.

The company will issue the duplicates within six weeks of submitting these documents at a nominal charge of Rs 200-500. The process may take longer if a third party raises objection to your public notice. Moreover, you will have to supply the final court order, along with the above-mentioned documents. Be prepared for other sundry costs, such as court fees, which typically does not exceed Rs 2,000, lawyer's fee, which can range from Rs 20,000 to Rs 2 lakh. Reputed law firms may even charge Rs 5 lakh, depending on the work that needs to be done.

 Bank deposit receipt

To apply for a duplicate fixed deposit receipt, submit a statement to your bank, clearly mentioning the amount and date of receipt, and explaining the manner in which the receipt was lost. If the bank is satisfied with your statement, it will issue a duplicate copy. However, it may insist on an indemnity bond, along with approved sureties or a bank guarantee. The cost is unlikely to exceed Rs 200. Don't forgetto lodge a police complaint and publish a notice in newspapers. If you don't have relevant details, you will have to apply to the bank for an inspection of records. "This is a time-consuming process," warns Suresh Surana, founder, RSM Astute Consulting.

 Academic certificates

In this case, you will again need to lodge a police complaint, but a public notice may not be necessary. After this, apply to your college/university or exam board for a duplicate certificate. "You may be asked to furnish proof of identity and a copy of the police complaint," says Surana. The fee is typically less than Rs 500.

Source: Economic Times

How To Manage Your Financial Documents In Proper Manner?

Rajat Vinayak is not adept at paperwork, financial or otherwise. He knows he is losing money because he is unable to find the bills he needs to claim official reimbursable expenses. He ends up paying for the maintenance and servicing of new equipment because he can't find the warranty cards and payment receipts.

At the time of filing returns, he finds he has not maintained the records that will allow him to claim deductions. Rajat realises that his poor papermanagement habits are hurting him financially. What can he do to make it easier to deal with papers generated in the normal course?

Rajat needs to do three things to ensure that he handles his paperwork better. He must sort it immediately, keep it updated and dispose of the documents that are not required. This will require a little discipline, but it will go a long way in making his life simpler. The first thing he must do is to make a list of important documents that need to be kept safe. He may have to refer to some of these, such as bank statements, credit card statements, investment records and tax documents, as these will be current in nature.

Rajat should keep separate, properly labelled, files, marked by year, in which be must file his documents. He should also store these in a place where they are easily accessible. Important papers, such as insurance policies, property documents, will and warranty cards, which are active but may not be referred to frequently, must be stored safely. Rajat should also ensure that he informs his wife about where these documents are kept.

Rajat should also earmark a place for keeping his bills through the week and designate a day to sort these. Bills for payment, expenses to be claimed and similar documents should be dealt with immediately. Rajat will find that when he sorts his papers every week, the volume doesn't seem intimidating and is easier to manage.

 Shredding is the third important step that will help Rajat get his paperwork in a manageable shape. Bills, receipts, credit card slips, old investment statements, expired warranty cards, old insurance policies should all be shredded to avoid clutter. Others like bank statements and tax records should be maintained as long as it's legally required.

During the weekly sorting exercise, the papers that don't need to be maintained should be shredded. Once a year, Rajat should review his file of important documents and shred what doesn't need to be kept.

Source: economic times

How To Keep Your Financial Documents In Order?


"What is your net worth?" This simple question from a financial advisortotally stumped a Mumbai-based businessman.//He had two cupboards full of papers – documents related to real estateagreements, fixed deposits, insurance policies and premium receipts, income tax filings, mutual fund investments and share certificates.

He definitely knew that he was worth something, but he just couldn't put a number to it. He just didn't have any idea of the worth of his investments or his liabilities to arrive at a ballpark figure. The amused advisor gave the businessman six folders, one each for insurance , income tax, real estate, shares, mutual funds and fixed deposits, and asked him to sort the documents accordingly.

Yes, finally the businessman figured out his net worth; but only after hours of hard work. According to investment experts, many individuals have documents scattered all over the place, some in office, some at home, some in a locker, some in some drawers. A part of it may be sorted systematically, and the remaining work is left for another day.

Such attitude can spoil all the hard work, say financial experts. What is the use of an insurance plan if it doesn't help the dependents to cope with the loss of the breadwinner ? Or what is the use of investments if you can't liquidate just in time? Financial advisors can recall many instances where the family came to know about the existence of an insurance policy or valuable investments accidentally after the death of the head of the family.

"Arrange your documents into two sets. One, where you need to store physical documents like PAN card, passport, insurance policies, and physical shares. The other set could include documents likemutual fund statements, bank statements, where retaining physical copies is not important," says Mukund Seshadri, partner at MS Financial Planners.

"Involve your family and keep them informed about your investments so that it can be passed on to them with ease in case there is a need. Check your documents for accurate names tallying with your PAN card and nominate a person if you have not done so," says Vishal Dhawan, chief financial planner at Plan Ahead Wealth Advisors.

 SORTING THE DOCUMENTS

Keep the originals of documents related to your life insurance policy, medical insurance policy, PAN card, passport, driving licence safely. Not having original copies of these may cause a lot of inconvenience.

"Keep these documents in one separate folder. You could also get them scanned and store them in your computer or on a pen drive," says Vishal Dhawan. If you hold physical shares, get them dematerialised immediately through a depository participant like a bank or a broker. "Today you cannot sell physical shares. In case you need the money, you would be stuck. Hence get them dematerialised at the earliest," says Sumeet Vaid, founder, Ffreedom Financial Planners.

 Having a demat account also helps to take care of your dividend warrants . All the dividends coming in for such shares will electronically be credited to your bank account, and hence there is no risk of losing them. In case of mutual fundinvestments , there are multiple statements which you receive. There is a quarterly statement from the registrar and an annual statement from the mutual fund you have invested in. Storing all statements in physical form is not essential.

"Your last transaction statement will give you details of all the investments in your folio," says Vishal Dhawan. If you are comfortable, try storing them electronically. "We suggest investors open a new e-mail ID and register that with mutual funds. Once this is done, all your transaction statements will go to this mail ID, and it will be easier for you to locate them when required," says Lovaii Navlakhi, founder and CEO, International Money Matters.

While sorting the physical documents , you must also ensure that the documents are in order. For example , ensure that in a mutual fund statement the names of the holders should match that on the PAN cards. In case you have investments in a single name, ensure that you nominate a person. You can also scan important physical documents and store them electronically.

Many firms like ICICIDirect , oneassist and Perfios, among others, offer you electronic lockers to store your financial documents. The facility serves as a backup and retrieval tool for important documents . It can be used to store electronically scanned copies of important documents like legal agreements, policy documents, degree certificates and bank statements.

"In case you were to lose any physical copy of any document or need a printout and you are not carrying one, you can always access these copies from anywhere in the world," says Hariharan M, vicepresident , ICICI Securities.

 KEEP YOUR FAMILY INVOLVED

Don't keep your investments and insurance policies as the biggest surprise for your family after your death. Keep at least one member of the family in the loop, so that the person can do the needful. "At least one person close to you should be aware of your finances. In case people are hesitant to talk about numbers with their family or children, we ask them to share details with a close friend or a family member," says Harshvardhan Roongta, chief financial planner, Roongta Securities.

You can also inform your family about these matters without giving them the numbers. For example, you can casually mention that you have a life insurance policy from XYZ company . Or you have invested in some mutual fund schemes. "Whenever we make a financial plan or review it, we always insist that both partners are present for each meeting. In case a person is single, another family member must be present," says Mukund Seshadri.

Source: Economic Times


The 7 Habits Of Highly Effective People

Habit 1
 Be Proactive®
Take initiative, Manage change, Respond proactively, Keep commitments, Take responsibility and practice accountability, Create positive business results.

Habit 2
 Begin With the End in Mind®
Define vision and values, Create a mission statement, Set measurable team and personal goals, Start projects successfully, Align goals to priorities, Focus on desired outcomes.

Habit 3
 Put First Things First®
Execute strategy, Apply effective delegation skills, Focus on important activities, Apply effective planning and prioritization skills, Balance key priorities, Eliminate low priorities and time-wasters, Use planning tools effectively, Use effective time-management skills.

Habit 4
 Think Win-Win®
Build high-trust relationships, Build effective teams, Apply successful negotiation skills, Use effective collaboration, Build productive business relationships.

Habit 5
 Seek First to Understand Then to Be Understood®
Apply effective interpersonal communication, Overcome communication pitfalls, Apply effective listening skills, Understand others, Reach mutual understanding, Communicate viewpoints effectively, Apply productive input and feedback, Apply effective persuasion techniques.

Habit 6
 Synergize®
Leverage diversity, Apply effective problem solving, Apply collaborative decision making, Value differences, Build on divergent strengths, Leverage creative collaboration, Embrace and leverage innovation.

Habit 7
 Sharpen the Saw®
Achieve life balance, Apply continuous improvement, Seek continuous learning.

(ICEU) has threatened to go on nation-wide strike


Insurance Corporation Employee’s Union (ICEU) has threatened to go on nation-wide strike to protest against the government’s proposal to hike Foreign Direct Investment (FDI) cap in insurance sector to 49% from current 26%.

Government is planning to introduce a bill during the ongoing parliament session seeking to increase FDI limit in insurance sector to 49% and sell the stakes in public sector insurance companies.

As per ICEU, they consider this a dangerous move against the welfare of the nation and to the future of insurance industry.

ICEU also said that government’s argument of industry seeking foreign investments is baseless. It said that in the last eleven years insurance sector has attracted only Rs 6,831 crores of foreign investments.

While, during the 11th five-year plan, Life Insurance Corporation of India (LIC) has made contributions of Rs 7.04 lakh crores to the government and in the last 11 years, the dividend amount presented to the government by the LIC was Rs 7,848 crores, higher than the FDI received by the insurance sector.

ICEU has already sought 200 parliamentarians support in this matter. ICEU also said that employees across insurance sector will go on strike if bill is passed in the parliament.  The union will also conduct a public meeting on 14 December 2012 in Chennai in which representatives of various political parties would participate.

Walmart lobbying bill hits Rs 125 crore on India entry

WASHINGTON/NEW DELHI: Global retail giant Wal-Mart — waiting for years to open its supermarkets in India — has been lobbying with the US lawmakers since 2008 to facilitate its entry into the highly lucrative Indian market. 

According to lobbying disclosure reports filed by Wal-Mart with the US Senate, the company has spent close to $25 million (about Rs 125 crore) since 2008 on its various lobbying activities, including on the issues related to "enhanced market access for investment in India". 

In the last quarter ended September 30, 2012 itself, the company spent $1.65 million (about Rs 10 crore) on various lobbying issues, which included "discussions related to FDI in India". 

During the quarter, Wal-Mart lobbied for its case with the US Senate, the US House of Representatives, theUS Trade Representative (USTR) and the US Department of State, according to its latest quarterly disclosure report. The companies are allowed to lobby for their cases in various departments and agencies in the US, but they are required to file their lobbying disclosure reports every quarter with the US Senate. 

So far in 2012, Wal-Mart has spent more than $3 million or about Rs 18 crore on its various lobbying activities, including those related to India. As per Wal-Mart's lobbying disclosure reports, the company has continuously lobbied for its India entry since 2008, except for a few quarters in 2009.

Votebank politics has destroyed the country: Modi

Gujarat Chief Minister Narendra Modi today launched a sharp attack on Congress alleging its "votebank politics has destroyed" the country and the party had no agenda for the assembly elections. 

The BJP stalwart also targeted Congress chief Sonia Gandhi and Prime Minister Manmohan Singh as campaigning for first phase of polling on December 13 reached its final stage. 

"Mr Prime Minister, Soniaji and friends from Congress due to your votebank politics the country has been destroyed", Modi said. 

Apparently replying to Gandhi's comments at a poll rally at Dakor town earlier in the day, Modi said Congress was not a "service (sewa)-oriented party", as claimed by her, but a "mewa-bhawik" (benefit seeking party) party." 

Addressing people across 53 places simultaneously through 3D holographic projection technology, he said "caste and votebank politics of Congress has destroyed the country." 

"Congress has no agenda for this election," Modi charged. "It seems Sonia Gandhiji was reading a speech prepared for the 2007 election instead of 2012 election. She said there are 57 dark zones (talukas) in Gujarat. But she is unaware that my government has lifted them (talukas) out of dark zones." 


"Dark zones" are the talukas where electricity connection is not given to anybody to draw underground water as water level has receded. 

Modi once again targeted the Prime Minister. "The Prime Minister has not been able to rise above the politics of votebank," he said, hitting back at PM's remarks that time has come to "liberate" Gujarat from divisive politics. 

"I thought being the Prime Minister of the country he would treat all the states equally. But hearing him speak a language of minority and majority would hurt any Gujarati," Modi said, adding six core Gujaratis live like a family. 

Modi said there was "contradiction" between the statements of the Prime Minister and the Congress chief. "Sonia Madam says there is no development...while PM says development has taken place but from funding of Delhi."

LIC unfairly favoured, concedes Irda chief


Says recent govt concession to state-run insurer on investment norms is unwise revised guidelines on product design, bancassurance to be issued in a few weeks
BS Reporter / Hyderabad Dec 08, 2012, 00:13 IST

The Insurance Regulatory and Development Authority ( Irda) has said it cannot allow the same relaxation on investment norms for private insurers which the finance ministry recently gave to government-owned Life Insurance Corporation of India (LIC). The latter was recently allowed to invest up to 30 per cent in a company by the ministry, up from the 10 per cent hitherto applicable for all.

"The regulator is very clear that the insurance industry has to be regulated on prudential norms. We will not sacrifice those norms," said J Hari Narayan, chairman of Irda.


Queried on the duality, he conceded it was not defensible but he was helpless. "Our view is that it (the finance ministry favour to LIC) is not in conformity with the Act. But I understand the ministry of law has clarified that the view of Irda is not correct. They said the government has the power to frame the investment regulations for LIC. The regulator only operates according to the law enacted by Parliament. If the ministry of law says both are legal, then it's legal. What (can) we do?" he said here on Friday.


Asked if it was case of some being more equal than others, he agreed this was the reality. Private insurers had recenlty sought an increase in the current investment ceiling in a company to 20 per cent, something Narayan had refused to consider.

Product guidelines
 Hari Narayan said the revised product design guidelines would be out by the end of this year. "We are working with the industry to figure out a design template about what we wish to see in products and what we don't. The guidelines are in an advanced stage of evaluation. Hopefully, they will become regulations shortly," he said.

If a company wishes to sell a pension product, it must have the responsibility to provide the annuity. If a pension product is not going to end in a pension, then it cannot be called a pension product. Similarly, any life insurance product must have a minimum guaranteed death benefit. Otherwise, it is not a life insurance product. The guidelines would include templates like these, he said.

"There are certain fundamental principles we cannot compromise on in the interests of policyholder protection," he said.

He said the issues raised by companies in the sector at a meeting with the finance minister earlier this year were already a part of the draft guidelines. However, the meeting helped expedite and also attain a consensus opinion on the direction the regulator and those in the sector wished to go.

Bancassurance norms
 The guidelines on bancassurance, the norms under which banks are allowed to sell insurance products, would be ready by the later part of January 2013, according to him.

On whether a bank should sell the products of only one insurance company or more, Hari Narayan said banks had misunderstood the insurance laws. "If banks wish to perform the function of an agent, then ]they can have a tie-up with only one company. Supposing they wanting to tie up with more than one company they should function like a broker, and then this particular bank comes under broking regulations," he said. Banks cannot, he held, say they want to function like a broker but also want to be an agent.

Products in for a change
 Hari Narayan said the sector was is in for a change in terms of the kind of products people wished to buy. He cited the experience of countries in Europe and America, where personal incomes were on the rise. Pension and direct savings-oriented products with smaller tenure in those countries had become popular, while endowment products had practically vanished.

"I would think that even in India, increasingly, the trend will be in that direction. It is not yet so clear because traditional products are still selling well. But I think in time this will change," he said.

Trend
 The life insurance sector, which has seen a decline in growth over the past few years, has stabilised and there won’t be negative growth hereafter, though growth this year would be close to zero, he said. As the non-life sector is proportionately very small compared with life insurance, unlike in other countries where both are of equal size, growth opportunities in this segment were more, he said. The insurance premiums collected in India were a little less than five per cent of GDP, a healthy number, he said.

Hari Narayan demits office in February. He said he was hopeful of finalising the regulations on the health sector and on micro insurance before the end of his term.

Please do not keep me a SECRET...Refer me to Your Family n Friends.

If your ATM card is lost pls call 1800-112211 / 080-26599990 

vinay mohanty

Investments by LIC in state-owned units see an erosion of Rs 5,170 cr in market value

NEW DELHI: Investments by Life Insurance Corporation of India to bail out some of the government's bigticket share sale in state-owned enterprises have lost Rs5,170 crore, or almost a quarter, in value.

The country's largest financial institution had to pick up close to 70% of the government's combined equity offerings in NTPCBSE 0.66 %, NMDC BSE 0.64 % and ONGC BSE 0.47 % because foreign institutional investors as well as local private sector fund houses were put off by the high floor price. 

Since LIC is a long-term investor that largely dips into funds of traditional insurance policies to subscribe to stocks sold in government's divestment programme, it is spared of mark-to-market (or MTM) accounting losses arising out of decline in investment value.

"Mark-to-market changes are merely notional, reflecting the appreciation or depreciation of value, and not actual profit or loss," said an LIC official. Justifying the investments, he said, "Public sector undertakings are pioneer and market leaders in their respective sectors and many of them have strong fundamentals, huge potential for market share and high intrinsic valuations."

LIC, however, has to take MTM hit from dip in stock prices whenever it buys shares from funds collected by selling unit linked insurance policies. It is understood that due to the demand and pricing of PSU stocks, LIC uses the traditional fund to subscribe to selloff offers.

The government had raisedRs30,560 crore between February 2010 and March 2012 from these three divestments. The market value of these investments has slipped even though the BSE Sensex gained 21% since February 2010 and 10% since March 2012. About a month ago, LIC also bought a substantial part of theRs807-crore divestment of Hindustan CopperBSE 1.16 % at Rs156 a share. The stock is now trading at less than Rs153.

"As long as LIC meets the prudential norms, the regulator has no issue. It cannot comment on individual investment decision of any company," said IRDA chairman J Hari Narayan. Refusing to comment on specific investments, the official said: "LIC tends to manage its portfolio as a whole and generate good returns.

For the period ended September 30, 2012, its equity portfolio has shown fantastic appreciation on mark-tomarket basis." But, it's an unrealised valuation of investment and depends upon indices and parameters such as GDP growth predictions, published data on IIP and inflation, exchange rate, crude price, infrastructure spending, FII inflow and national and global scenario, he said, adding that the corporation has booked profits of more than Rs2,900 crore in the last three financial years from PSU stocks.

"LIC is the only white knight-....You can technically call such share sale disinvestment, but it is not. Out of LIC's multiple objectives, one of them seems to be helping the government reduce deficit," said Dhirendra Kumar, founder and chief executive of the fund tracker, Value Research.

"In India, the market capitalisation of top 1,800 companies is around Rs65 lakh crore and PSU companies account for more than 25% of the total market capitalisation. Therefore one cannot construct portfolio without PSU stocks. In the past, PSU stocks like Oil IndiaBSE 0.01 %, HPCLBSE 0.12 %, BPCLBSE 1.45 % and ONGC have given fantastic returns on investment over a period," said the LIC official. 

India Tops Global Life Insurance Density Rankings: WEF


New Delhi: India may rank low in terms of overall financial development globally, but it is the world’s top-ranked country in terms of life insurance density, the World Economic Forum (WEF) has said in its latest report.Life insurance density is measured in terms of ratio of direct domestic premiums for life insurance to per capita GDP of a country.

 As per WEF’s Financial Development Report 2012, India has been ranked 40th in terms of overall financial development of a country, but it is placed better than many larger economies like the U.S., U.K., Japan and China for life insurance density.

 India is followed by China, Japan, U.S. and U.K. in the top-five countries for life insurance density, WEF said. In terms of non-life insurance density, India is ranked third after China and the U.S. at top-two positions, but is ahead of countries like Germany, France, Japan and the U.K.

 Global consultancy giant McKinsey said in a recent report that Indian insurance sector is expected to see an exponential growth in 2012 amid increasing household incomes and higher premiums (as a percentage of the GDP).
 WEF said its report measures the financial development of 62 countries across various segments of their financial systems and capital markets. The overall rankings are based on more than 120 variables spanning banking financial services, financial stability and

 non-banking financial services among other factors.
 “Recent empirical research has found a strong positive relationship between insurance sector development and economic growth; this relationship holds quite strongly even in

 developing countries,” WEF said in its report. “Insurance also creates liquidity and facilitates the process of building economies of scale in investment, thereby improving overall financial efficiency,” it added.

vinay mohanty

Traditional Product Guidelines Likely To Be Out In 45 Days


Posted on December 4, 2012 by Akanksha

It is expected that much awaited traditional product guidelines for life insurance companies will be out in next 45 days.

According to revised draft policyholders will get back as much as 50% of their premiums, if a policy is active for three years that means that a policy will have a minimum Guaranteed Surrender Value (GSV) of 50%.

Minimum GSV is a sum of guaranteed surrender value and the surrender value of any subsisting bonus already attached to the policy.

Unit-Linked Insurance Plan (ULIP) already has such guaranteed surrender value.

Insurers say that GSV should have been left for the companies to decide. Minimum GSV will vary from one product to another in a company. So, it is not appropriate to mandate a specific value for it.

Since the cost of acquisition and execution for insurance firms are high, it will be difficult for them to operate, if the latest guidelines are implemented, prompting them to sell more traditional products than ULIPs.

These guidelines will also pave the way for Index Linked Insurance Plans (ILIPs). It will have similar structure as ULIP.

The draft has also given detailed specification on all products, death benefits and charges.

It is expected that almost all products would have to be re-filed when these guidelines will come into force.

Insurers will be given time till 31 March 2013 for group policies and 30 June 2013 for individual policies, to enable them to withdraw products from the market and re-file them, as per the new guidelines.


vinay mohanty

Ulips are more expensive than MFs


Neha Pandey Deoras / Mumbai Dec 03, 2012, 00:57 IST
The new marketing line amid insurance agents is “unit-linked insurance plans ( Ulips) are cheaper than MFs”. This argument is based on the expense ratio that mutual funds charge vis-a-vis Ulips. But ask a financial advisor and he will strongly advocate a mutual fund for investment purposes and a term plan for insurance.

Even in terms of overall costs, an MF score. In September 2010, the Insurance Regulatory and Development Authority ( Irda) had issued guidelines for Ulips, aimed at capping the charges on the product, which in the first year could be as high as 100 per cent of the premium. The guidelines were a huge help for customers.

In August 2012, the Securities and Exchange Board of India ( Sebi) introduced measures for the insurance sector. Sebi allowed funds with assets worth less than Rs 100 crore to charge 3.12 per cent in expense ratio annually. This led many to believe that mutual funds have become expensive, compared with Ulips.

MUTUAL FUNDS
0.5% has been added to historical ratios as  expense ratios are likely to go up due to new regulations
             HDFCTop 200   BSLFrontline        DSP Equity
Year 1 2.87                 3.00                            2.85
Year 2 2.69          3.00                      2.88
Year 3 2.70                 3.00                             2.79
Year 4 3.00           3.00                              2.61
Year 5 2.40                2.85                              2.59

Such a notion, however, might be misplaced. For one, Ulips levy more than one cost in the first five years of investment but MFs don’t. For another, Ulips charge under various heads such as premium allocation charge (PAC), fund management charge (FMC), policy administration charge, mortality charge, et al, while the MF only levies an expense ratio (the fee charged by a fund house to manage and operate the fund). Therefore, despite a higher expense ratio, MFs work out cheaper than Ulips.(BREAK-UPS OF PLANS)

Sumeet Vaid, founder and CEO of Freedom Financial Planner, says Ulips are expensive products and, hence, should not be used as an investment vehicle. While insurance plans are best for risk coverage, Vaid advises one to stick to MFs for investment needs.

Sample this. HDFC SL Progrowth Flexi charges 7.50 per cent as PAC and 1.35 per cent as FMC in the first policy year. However, the plan does not levy any policy administration fee and mortality depends on the age to be insured. The cost of investment in the first year is 8.85 per cent (excluding mortality). For instance, if you are paying a premium of Rs 5 lakh for a Rs 50 lakh cover, your cost of investment in the first year would be Rs 44,250. The product levies a similar charge in the second year. However, in the third, fourth and fifth years, the charges decrease by two per cent. From the sixth year, the policies do not charge PAC but a policy administration fee is charged at Rs 6,000 per annum or 1.2 per cent, whichever is lower. FMC continues to be levied at 1.35 per cent every year.

Similarly, Aegon Religare iMaximize Plan does not levy a PAC but it charges a policy admin fee of Rs 1,200 a year and FMC of 1.35 per cent annually in the first five policy years. Taking the above example, the cost of investment would be Rs 7,950 yearly (FMC of Rs 6,750 + Rs 1,200). This is besides mortality fee, which increases with age. Five years of investment is considered because the lock-in period for Ulips is five years.

Bajaj iGain III is an even more expensive product. It levies a PAC of two per cent, FMC of 1.35 per cent, and varied policy admin fees. In the first year, the investment cost would be Rs 17,134. In the second year, the cost is Rs 17,153, in the third year Rs 17,173, and so on. This excludes mortality fee.

We assume the investor will stay invested throug the policy term. However, if the investor wants to discontinue the policy, there are charges for that as well. All the three policies mentioned above charge six per cent of the annual premium or fund value not exceeding Rs 6,000 in the first four policy years.

In comparison, HDFC Top 200 (an equity diversified mutual fund scheme) levies only 2.87 per cent of the investment as expense ratio. For an investment of Rs 5 lakh, the scheme would deduct Rs 14,350. Birla SunLife Equity (an equity diversified mutual fund scheme) charges 3 per cent annually, or Rs 15,000, and DSP Equity charges between 2.59 per cent and 2.85 per cent in the first five years of investment. That is, between Rs 12,950 and Rs 14,250. Here, 0.5 per cent has been added to the historical expense ratios, because the expense ratios are likely to go up on the back of the new regulations.

While mutual funds can give 10-12 per cent annually, financial planners say Ulips mostly give seven-eight per cent annually if you have invested only in equity schemes.

Take your pick.

“Despite a higher expense ratio, after cost deduction, mutual funds invest a larger portion of the invested amount compared with Ulips, because Ulips have more than one cost levied on the investor. Secondly, most of the costs are in percentage term, thus eating into the invested corpus,” says a financial planner.

vinay mohanty

LIC will launch a ULIP plan to take market sentiment


After nearly two years, country’s largest insurer, Life Insurance Corporation of India (LIC) will launch a Unit-Linked Insurance Plan (ULIP) with intention to take advantage of prevailing positive sentiment in the stock markets.

This would also help LIC to achieve its target of Rs 45,000 crores of new premium income in financial year 2012-13 and increase its market share.

At present, LIC has market share of 75% in terms of premium and 81% in terms of number of policies sold. LIC’s last ULIP –Samridhi Plus –, a guaranteed NAV plan, was launched in February 2011.

ULIP used to be a favorite investment option for investors pre-September 2010, when Insurance Regulatory and Development Authority (IRDA) came out with stiff norms. IRDA mandated minimum mortality cover and increased lock-in period from three years to five years. As a result, ULIPs took a huge beating and ULIP premiums, which accounted for 90% of first-year collection of life insurance companies, saw their share fall to less than 30%. As of 31 March 2012, share of ULIPs in LIC’s premium was 20% down from over 70% in pre-2010 period.

Private life insurers view this development of LIC as positive step for the industry. If LIC goes aggressive on ULIPs and launches new products, it will benefit the industry as a whole. LIC has greater reach and with its huge agency network it will be able to reach thousands of customers and explain the advantages of ULIPs. And people would be able to re-accept ULIP as good product for long term investment purpose. LIC’s these efforts would be able to bring ULIPs back to prominence in the market.

In addition, LIC will also launch a pension product shortly. LIC has filed both products with IRDA for approval and expecting approvals soon.

On the pension product front, LIC is the sole player till now. In January 2012, IRDA has said that pension products will have to guarantee an assured benefit in the form of non-zero rate of return that would be disclosed upfront. New regulations had led to slower approval of pension products which has resulted in dearth of pension products in the market.
 Categories: News | Tags: IRDA, LIC, Life Insurance Corporation of India, Pension Products, ULIP

vinay mohanty

LESSONS FOR PVT INSURERS FROM LIC 'S LONGTERM SUCCESS

vinay mohanty

Reliance Life tops customer complaint list for FY12: Govt 01-Dec-2012 Source : PTI


According to the data provided by Minister of State for Finance Namo Narain Meena in the Lok Sabha, as many as 50,807 complaints were reported against Reliance Life in 2011-12, followed by HDFC Standard Life (35,218) and Bajaj Allianz (22,390).
However, all these companies attended to almost all of the complaints in the same year, the data revealed.
The data further showed that a total of 2,57,313 complaints were against the 23 insurers in 2011-12 of which 2,56,196 were attended to.
There were 2,936 complaints related to death claims against Bajaz Allianz followed by HDFC Standard (461) and Tata AIG (395).
In policy servicing segment, maximum complaints were against HDFC Standard (5,781) followed by Reliance Life (5,251) and Tata AIG (4,264).
As far as proposal processing is concerned, there were 33,847 complaints against Reliance Life and 14,451 against Future Generali.
The data further revealed that in the unfair business practice category, largest number of complaints were against HDFC Standard followed by ICICI Prudential and Reliance Life.
Insurance regulator IRDA has a centralised system -- integrated Grievance Management System (IGMS) -- which creates the central repository of complaints of policyholders against all insurance companies.
"Action, including imposition of penalties and warnings, is taken against the companies where deemed necessary," Meena said.


At present, Life Insurance Corporation of India (LIC) is the only player that offers pension products in the market. According to private life insurers, other players in the segment are likely to follow suit and launch products. Apart from HDFC Life, several other private life insurance companies have filed their product with the insurance regulator
vinay mohanty

LIC pay direct

The old online premium payment process of LIC, ask you to register on LIC India website with a User ID and password. But If you forgot your user id and password then you have no option but to go to LIC branch and pay the premium. LIC now has introduced a new payment method - LIC Pay Direct, with which you can pay your LIC premium payment without registering. 

Details You Need - Policy No, Premium Amount, Date of Birth of the Policyholder, Email ID and Mobile No. 

Things to Take Care
1. Online premium payment should be made by the policyholder himself. No third party (mother,father,brother, sister, friends etc.) premium payment should be made using LIC Pay Direct.
2. Please provide correct and valid mobile number and email id. As digitally signed receipt would be emailed to you for your record to this e-mail id. To view the LIC Premium Receipt you need to have acrobat reader version 6 and above. 
3. You can pay via LIC Pay Direct, using Internet Banking / Credit Card / Debit Card. International Credit or Debit Cards are not acceptable.
4. If the premium amount is debited from your Bank Account but error page is displayed. Don't repay again, first check with your bank whether your bank account/card is already debited/charged with the amount of earlier transaction. If it's been charged then a digitally signed LIC Premium Receipt will be sent to your email id in three working days after receiving the confirmation from your Bank. If not then try again. 
5. If you won't get LIC Premium Receipt in three working days then you can report it to following email id - bo_eps1@licindia.com (with policyholder's name, policy number, premium, mode of payment and date of payment etc.)
vinay mohanty

ID Proofs Compulsory During Train Journey from 1-12-12


ID Proofs Compulsory During Train Journey in All Reserved Classes from 1st December 2012
With effect from 01.12.2012, one of the passengers booked on a ticket for undertaking journey in any reserved class will have to produce any one of the prescribed proofs of identity failing which all the passengers will be treated as travelling without ticket and charged accordingly.
This provision shall, however, not affect the existing provision of Tatkal scheme where during the journey, the passenger is required to show the original proof of identity indicated on the ticket.
The number of prescribed proofs of identity have been increased from nine to ten by adding following identity card to the list of prescribed proofs identity:-
“Photo identity cards having serial number issued by Public Sector Undertakings of State/Central Government, District Administrations, Municipal bodies and Panchayat Administrations”
This information was given by the Minister of State for Railways Shri Kotla Jaya Surya Prakash Reddy in written reply to a question in Rajya Sabha today.
Best Regards

vinay mohanty

FM Vs IRDA over LIC investment percentage


New Delhi, Nov 20 (TruthDive) : IRDA has taken strong exception to the sanction given to LIC to increase its stake to 25% in listed companies.

As per IRDA-the regulator of all insurance companies,the maximum limit for holding stakes is only 10%. The Finance Ministry(FM) move is seen as putting LIC corpus fund at risk and endangering its policy holders.

IRDA is also peeved that FM has not taken its objections and gone ahead with the move. FM officials said that it had sent the proposal to the Law ministry for detailed study and it got the nod to go ahead. The move is to make LIC make purchase of shares in PSU listed for disinvestment. FM has been struggling to sell the stakes in these PSUs but officials in several ministries have been creating hurdles and till date no share has been sold.

The IRDA 1999 Act controls all insurers and an amendment to it states that no insurance company can invest up to 10% of its corpus fund. To circumvent this, FM will issue a gazette notification that gives it power to govern LIC. The move by FM would allow LIC to invest Rs 50,000 cr in equities and it need not sell stakes in 78 firms where it has stakes a little over 10%.

LIC is only too willing to follow the FM’s orders and is quite relived to be away from IRDA control. LIC officials say that IRDA is not taking a practical approach. It treats LIC on par with other companies with lesser corpus fund.

LIC has a Rs 13, 000 lakh cr base while others are in the Rs 10,000 cr range. The only option for IRDA is to go to the Financial Stability Development Council but here again it comes under FM, so it is not hopeful of any favourable decision. This is the second confrontation of the FM with a regulator. It recently locked horns with RBI over interest rate cut.

Lessons for private insurers from LIC’s long-term success


Kamalji Sahay Posted online: Tue Nov 20 2012, 02:38 hrs, ET
 During the 12th year of liberalisation of the insurance industry, there is a sudden lull in the market.

There is no excitement on any front and all the noise regarding too many regulatory interventions has died down. The half-yearly results, as on September 12, do not give any indication of a once-booming industry bouncing back. Some kind of uncertainty is pervading the whole atmosphere.

Those who used to speak of the advent of a new era have withdrawn themselves from the limelight. This is, of course, a very unfortunate situation for an industry vital to the economy and these developments reflect the truth, whatever be the sporadic announcements from Hyderabad, Mumbai and Delhi regarding inducing growth through various strategic decisions. At this juncture of dilemma, it will be worthwhile to look at the inherent strengths of India’s largest insurer — Life Insurance Corporation — as this behemoth has not only survived the liberalisation, but has also regained its market share after initially losing nearly 50% to the private sector.

Today, LIC is not only the market leader, but also, to the utter disbelief of the experts who predicted a huge erosion in its ability to protect its turf in the face of innovative products and state-of-the-art service standards being introduced by the private players, the public sector organisation has conceded just over 1% average market share to the 23 private sector players. Interesting, isn’t it?

On Diwali, an old colleague shared his experience that out of nearly 100 SMSs of greetings that he got, nearly 80% were from insurance agents with whom he had worked as an LIC branch manager 20 years back. I think the secret of LIC’s success lies here.

Each salesman of this institution who has survived for at least five years is virtually a moving office in its locality and is trusted by the customers for all insurance needs. A strong force of such sales people has been created by LIC’s marketing officials through a continuous handholding in the field for enabling them to successfully launch themselves on a very rewarding career. 

I have met LIC agents who literally worship their mentors, who they look upon as selfless seniors who place business before self and for whom the interest of the organisation is uppermost. For 20 years, the team, mentioned to me by my colleague, has been contributing and earning loyalty of customers through their continued visibility and presence in the market. In the process, they have taken care of their family and grown with the organisation. 

With a team of such dedicated workers, any organisation is sure to grow and become highly competitive. During my close interactions with private sector players, I gathered that they are grossly lacking in team building. 

There is no stability in the field force and the managers do not get involved with them at the field level. It is generally believed that pressure for performance will bring business and when somebody is not able to cope, he needs to exit. 

I vividly recall an occasion when I was a witness to a large business house planning its foray into insurance, holding meetings of the top team with only one motto: to be seen wherever LIC is. But the top man there said, “We will recruit a large number of youngsters in the sales force, squeeze them and then throw them out and the cycle will go on.” 

This was considered the recipe for a high-octane business performance. That day, I felt that the company is being launched with a basic flaw regarding the sales-force management and the company will never be able to come close to its target .The apprehensions proved correct.

Today, it is observed that in companies other than LIC, there is hardly any employee in the field force who can claim to be serving the company as advisor or sales manager since inception or for a fairly long time. In this situation, how can a company expect loyalty of its customers for 15, 20 or even more years? Life insurance, or any other insurance for that matter, thrives on long-term relationship.

To revive the industry, fundamentals of the business strategies are required to be examined, focussing on the essential character of the business. 

It is to be understood in the background of the exemplary success of the state insurer. 

The sales people are given utmost importance in the organisation and the seniors are in regular touch with them al the time. 

The motivation to sale comes from the top man in the organisation. The motivation to continue in the profession 

comes from the wonderful atmosphere that provides several reasons other than income to stick to the cadre. 

Too much dependence on IT has dehumanised an organisation’s relationship with the field force. I think the sales people slowly build an insurance company over a period of time and those who are in other functions support them to stay connected with customers and the market with the enthusiasm that fuels high performance.

The author is former MD & CEO of Star Union Dai-ichi Life Insurance

vinay mohanty

Online Shopping: 5 Ways to know the site you are using is safe


Online shopping is now a part of our life. How do you find out whether the site you are using is safe enough for making online payments? Harjot Kaur explains

Online shopping sites are proliferating at a rapid rate. From Flipkart.com to Snapdeal.com to Myntra.com to Jabong.com to ols.com, dozens of ecommerce sites have sprung up. Customers find it easy to shop online and ecommerce sites and their backers with deep-pockets believe that it is a segment that will grow into billions of dollars of online market.

However, many are wary of shopping online, wondering if it’s safe. After all, in the process, you are uploading and storing on the shopping site all your credit/debit card information, address and other details. Not all sites are safe. High quality of design has made it possible for websites to look swishy enough and nearly match the official websites of banks and online payment channels. With an increasing number of websites you can buy from, it has become difficult to tell the trustworthy websites/payment gateways from those that are not secure. It is not very difficult to detect fake websites and online payment systems, if you are vigilant and remember a few key points.

Here are some signs and symbols you need to look for on your web page or the online payment gateway while making an online payment or while shopping online. Additionally, some third-party data aggregators also help you assess the quality of an online payment portal and whether or not, the web page you’re using is secure.

1. Check for Secure Link
Check the address bar on your web page. If the website name says ‘https’, instead of ‘http‘, then it is secure. When you open a regular website, the name of the website starts with ‘http’. But when your website is secure, the name would start with ‘https’, as depicted in the following screenshot.

 ‘Https’ signifies that all information you put on the page from this point on will be transferred to the receiver only in encrypted format—a technology used for transforming information into signs and symbols till it reaches the receiver, where it is again transformed into regular text. So, anyone trying to view your credit card or bank accountdetails during the transmission process will not be able to do so; your details remain secure.

2. Security Lock at the Bottom of the Page
The lock icon that you see when making online payment is not just a picture. It is a sign of the security of the web page you are using. Some websites have this lock placed in the address bar while others would have it at the bottom of the page, depending also on the browser you use. Technically called a padlock, it indicates that the page uses an SSL protocol or a TLS protocol. These are data transfer security standards that encrypt data as well as authenticate the server you are using. You should only use websites that have the lock in ‘locked’ state; unlocked websites are not secure.

3. Third-party Verification Certificates
These seals of approval are given by associations of members including payment gatewaysand sites using those gateways. The logos and certificates shown below mean that the association has verified the entire platform of online payments being used by the merchant and certifies that no information is being stored on the merchant’s server or elsewhere.

 Visa and MasterCard are two globally renowned online payment platforms used by most merchants.

These logos, however, should not be trusted on a standalone basis since they can be easily cloned or copied to make the site look authentic. They should be looked at in conjunction with other security signs. However, if all other signs are there and the certificate is not, the site should not be fully trusted.  The SecureCode sign means that by providing information about your credit or debit card, your financial institution is automatically prompted to check out your SecureCode each time you use your card. Your bank does not share your information with the company whose website you are using to make the purchase and that is why you are secure. By providing correct SecureCode each time, you authenticate that you are the right user of the card.

4. Double-level Authentication

 Double-level authentication is a two-level authentication and identification process which verifies the data twice before the payment goes through—once by the merchant site and next by the bank’s site. This process is mandated by the Reserve Bank of India (RBI) and has to be followed by all Indian entities having payment platforms on their websites. In case this is missing, RBI guidelines are being ignored and you should not trust the website for good reasons. Double-level authentication looks like the screenshot shown above (for HDFC Bank); it could be different for different banks.

5. Third-party Aggregators
Other than the signs on the website itself, many third-party websites aggregate performance data for users to analyse information, for example, mywot.com. This site aggregates all comments that users have put up anywhere on the web, regarding the payment platform of the company you are checking for. With that information on hand, you will be able to know others’ experiences while making payment and whether the website is trustworthy enough. The site also assigns ranks, based on four parameters, displayed in the screenshot below, and authenticates whether the site is useful or not.

 Once you have checked for all these security factors, you should be comfortable enough for making online payments. You must also note down the contact details of the website, your transaction ID and the time at which you made the transaction. It is also in your best interest to take a screenshot of the ‘transaction successful’ page. In case of any dispute in payments, these precautions prove to be of vital importance.

vinay mohanty

IMPS – Online Money transfer in 30 seconds from your Mobile Phone


IMPS or Interbank Mobile Payment Service is a technology which offers an instant electronic fund transfer service through mobile phones between two banks in India. There are other two money transfer systems called NEFT and RTGS already in India, but they are not a mobile payment system like IMPS and they’ll  take some time to get settled. IMPS is a real time system of money payment.  The service has been developed by National Payments Corporation of India (NPCI), a section 25 company formed by Reserve Bank of India (RBI) and Indian Bankers Association (IBA). Here’s a testimonial from Harsh, who transferred money using IMPS…

Recently I issued a cheque from one of my account and did a NEFT transfer to build balance but NEFT failed to do the job in 48 hours, in the middle of night i started searching for how to do a instant transfer and then I got to know of IMPS. Registration happened instantly in matter of minutes and shockingly money transfer happened in micro seconds even faster than a google search – (via)

The transfer limit through IMPS is defined by RBI in the Mobile Payment Guidelines issued to banks. The customer can transact on IMPS subject to a daily cap of Rs. 50,000/- per customer overall for transactions through mobile for the funds transfer.
How to do Money Transfer using IMPS
 All you need to make a transfer through IMPS system is your mobile number and MMID number . MMID number is a 7 digit random number which you get by registering for IMPS facility with your Bank. But make sure your mobile phone is activated before you register for MMID. Note that both sender and receiver should have their phone and MMID number from their respective banks. Once you have that you can transfer the money using sms or internet banking . A lot of banks also provide a mobile application which you can download from bank website and install on your phone. Note that before sending the money to the receiver, you should register them once as you do for any bank account.  The image below gives you good idea on what needs to be done for carrying out an IMPS transfer.

Get Premium Content - Jagoinvestor Wealth Club

 What happens with your do a IMPS Transfer through Mobile ?

When you make a IMPS transfer, your sender mobile first sends this information to the sender bank , which checks the data; whether your MMID is correct or not and if it matches with what it has in its system. If it’s all correct, it debits the money from your bank account and transfers this to the NCPI server, which then transfers it back to the receiver’s bank. The receiver bank goes about checking everything again and then sends the status of the whole transaction to NCPI, which passes it back to Sender’s bank. Both Receiver and Sender are then updated about the transaction through SMS. All this normally takes just about  15-30 seconds for everything to happen and the money gets transferred near instantaneously.
5 Advantages of IMPS over NEFT and RTGS

 Let me enumerate 5 major reasons why you want to register with your bank for IMPS and generate your MMID as soon as possible. IMPS offers some major advantages over NEFT or RTGS money transfer and here they are
1. Instant Transfer of Money
When you do an IMPS transfer, it happens instantly within few seconds, so it’s practically real time money transfer, unlike NEFT or RTGS which works in batches and takes time in money transfer. Which means in case of emergencies, you can use IMPS and it will act like a fast money transfer mechanism

2. Transfer without Internet Connection You dont need a internet connection or a computer for IMPS transfer, you can just do the transfer using your mobile phone through SMS or using the mobile application, hence you can do the money transfer even when you are travelling, all you need a mobile connection 3. Money transfer even on Holidays and outside working Hours
You can transfer the money anytime, 24X 7. With NEFT or RTGS , you can’t do money transfer on holidays or even Sundays. You can’t do it outside the working hours defined by the banks. But with IMPS you can literally make transfers in early morning, midnight or whatever time you want.

4. No Need to disclose Bank account number and other details
All you need for making the transfer is mobile number and MMID , so you don’t need to disclose your actual account number or even the bank name.

5. Easy, Simple and Secure,Making a IMPS money transfer is so easy.  All you need is the MMID, Phone number and the amount. The money gets transferred easily so fast. It makes easy for those who fear technology and do not want to deal with it . You can teach this to your parents or some one who is not that technologically advanced.

IMPS Charges  The charges depends from banks to banks . While exact charges details you can find from your respective bank, it seems the charges are extremely low and are on per transaction basis, not on the limit of money. It seems to be Rs 5 per transaction (not confirmed) yet. Apart from the charges from banks for using the service, if you are doing the money transfer using SMS , you will have to pay standard sms charges . However if you use internet or the mobile application, there will be no charges apart from the service charges.
Money Transfer Limit under IMPS

 The limit is defined by RBI in the Mobile Payment Guidelines issued to banks. The customer can transact on IMPS subject to a daily cap of Rs. 50,000/- per customer overall for transactions through mobile for the funds transfer. Transactions up to Rs. 1000/- can be facilitated by banks without end-to-end encryption.
Which Banks are part of IMPS Facility

 As of now 52 banks are the members of IMPS facility. Some of them have started the IMPS service and some will start it very soon. Those are
ICICI Bank
Axis Bank
State Bank of India
Indian Bank
 Kotak Mahindra Bank
Oriental Bank of Commerce
Union Bank of India
Andhra Bank
 Canara Bank
HDFC Bank
Lakshmi Vilas Bank
Bank of Baroda
Indian Overseas Bank
Bank of India
Punjab National Bank
South Indian Bank
Vijaya Bank
IndusInd Bank
UCO Bank
Federal Bank
State Bank of Hyderabad
 Citibank
State Bank of Bikaner and Jaipur
Punjab and Maharashtra Co-operative Bank
The Thane Janata Sahakari Bank
Development Credit Bank
Dombivli Nagari Sahakari Bank
State Bank of Travancore
 Catholic Syrian Bank
Syndicate Bank
Yes Bank
State Bank of Patiala
 Allahabad Bank
Karur Vysya Bank
The Greater Bombay Co-operative Bank LTD
Corporation Bank
 IDBI Bank
Tamilnad Mercantile Bank
United Bank of India
Standard Chartered Bank
 Bank of Maharashtra
Central Bank of India
Dena Bank
Dhanlaxmi Bank
 ING Vysya Bank
Janata Sahakari Bank, Pune
Karnataka Bank
State Bank of Mysore
 The A P Mahesh Urban Co-operative Urban Bank
HSBC Bank

 you can look at the latest list of all the banks and their details here  What do you think about this technology ? Will it help in your financial life ? Are you going to use IMPS facility to money transfer through your mobile ?

vinay mohanty

CM Convention at pune address


Dear friend CM convention at Pune address
Shiv Chatrapati Kridapeeth,
(Balewadi Sports Complex),
Badminton Hall,
Mhalunge-Balewadi,
PUNE - 4110045
conform the same at branch

vinay mohanty

NEW CLUB MEMBERSHIP RULES AT A GLANCE

if you want to daunlod the same here is link: click on it
https://mail.google.com/mail/u/0/?ui=2&ik=3dbb943306&view=att&th=13ae147efbd41299&attid=0.1&disp=inline&realattid=f_h9a7l6vs0&safe=1&zw

vinay mohanty

If you are Loving Person you have everything


A woman came out of her house and saw 3 old men with long white beards sitting in her front yard. She did not recognize them. She said “I don’t think I know you, but you must be hungry. Please come in and have something to eat.”


“Is the man of the house home?”, they asked.

“No”, she replied.. “He’s out.”

“Then we cannot come in”, they replied.
In the evening when her husband came home, she told him what had happened.
“Go tell them I am home and invite them in!”
The woman went out and invited the men in”

“We do not go into a House together,” they replied.

“Why is that?” she asked.

One of the old men explained: “His name is Wealth,” he said pointing to one of his friends, and said pointing to another one, “He is Success, and I am Love.” Then he added, “Now go in and discuss with your husband which one of us you want in your home.”

The woman went in and told her husband what was said. Her husband was overjoyed. “How n ice!!”, he said. “Since that is the case, let us invite Wealth. Let him come and fill our home with wealth!”

His wife disagreed. “My dear, why don’t we invite Success?”

Their daughter was listening from the other corner of the house. She jumped in with her own suggestion: “Would it not be better to invite Love? Our home will then be filled with love!”

“Let us heed our daughter’s advice,” said the husband to his wife.
“Go out and invite Love to be our guest.”
The woman went out and asked the 3 old men, “Which one of you is Love? Please come in and be our guest.”

Love got up and started walking toward the house. The other 2 also got up and followed him. Surprised, t he lady asked Wealth and Success: “I only invited Love, Why are you coming in?”

The old men replied together: “If you had invited Wealth or Success, the other two of us would’ve stayed out, but since you invited Love, wherever He goes, we go with him. Wherever there is Lovefor all , there is also Wealth and Success!!!!!!”


vinay mohanty